Latest from BCA Research
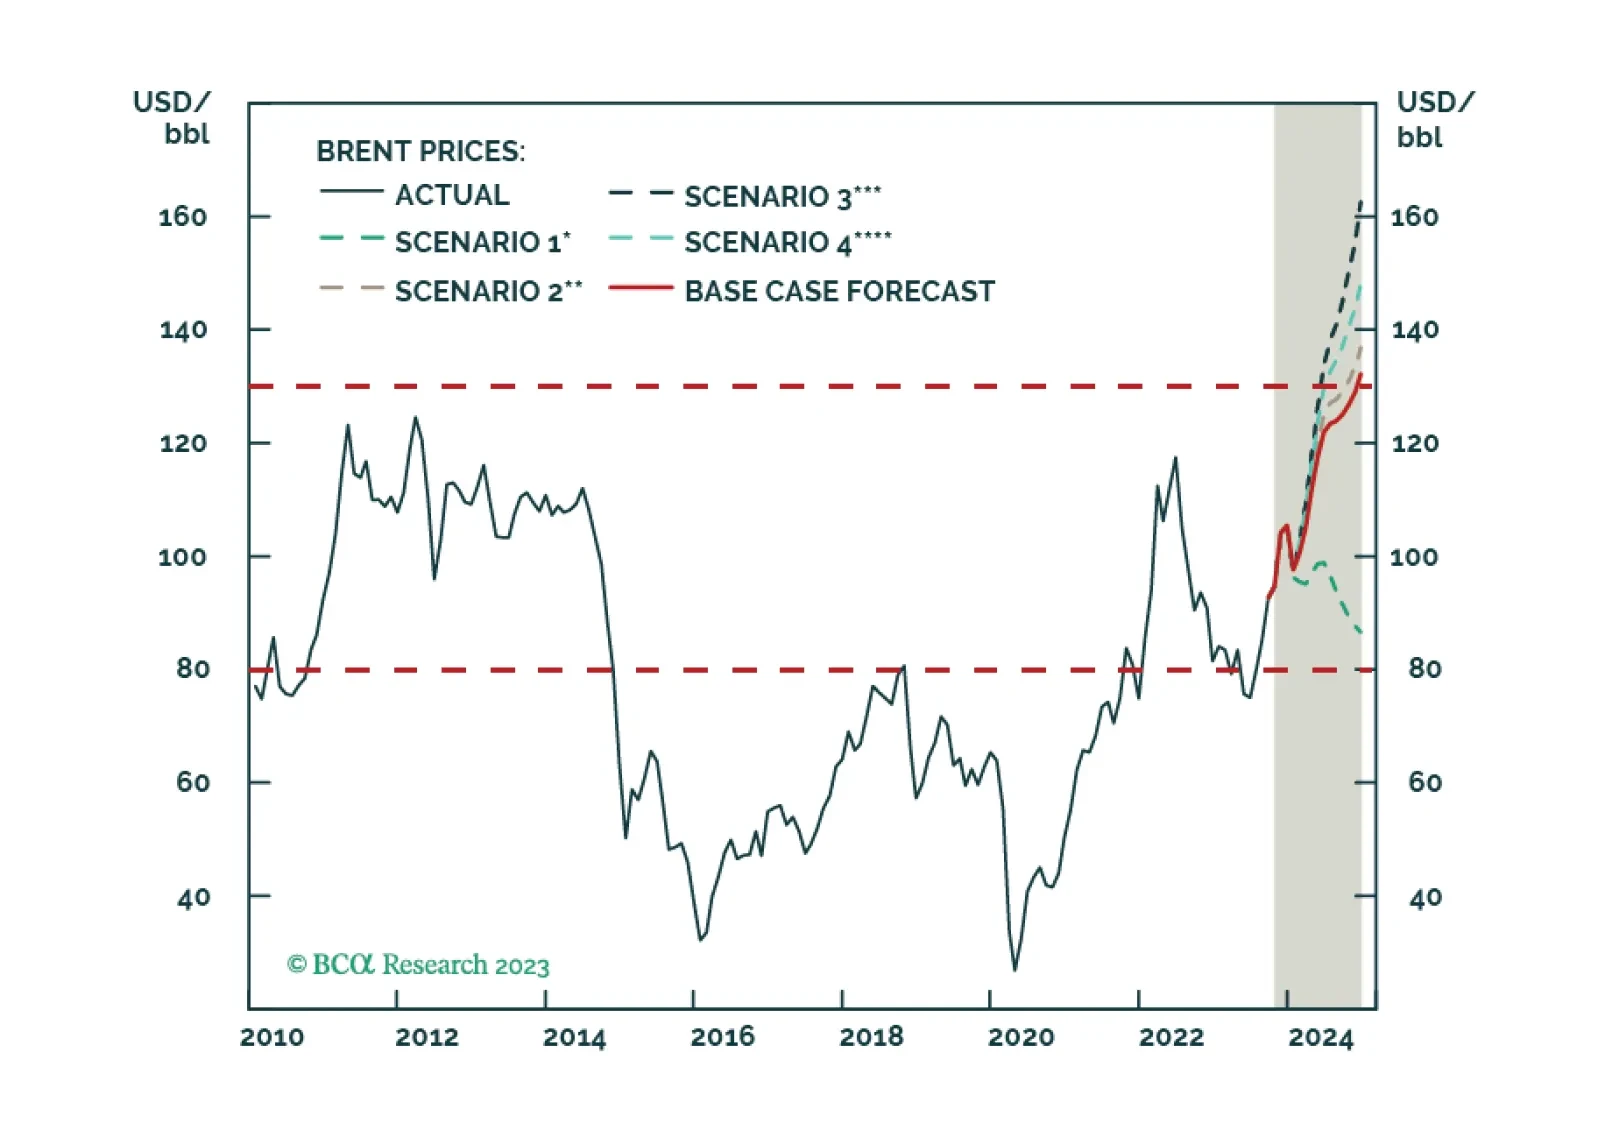
The US and core OPEC 2.0 are – wittingly or not – laying the groundwork for a price band with a floor and cap on oil prices – at $79/bbl and $130/bbl, respectively – “at least” to May 2024. This accommodates multiple goals for both. To meaningfully support policy, the US would need to scale up purchases to refill its SPR. We remain long the XOP and COMT ETFs for direct exposure to energy E+P equities and commodities.
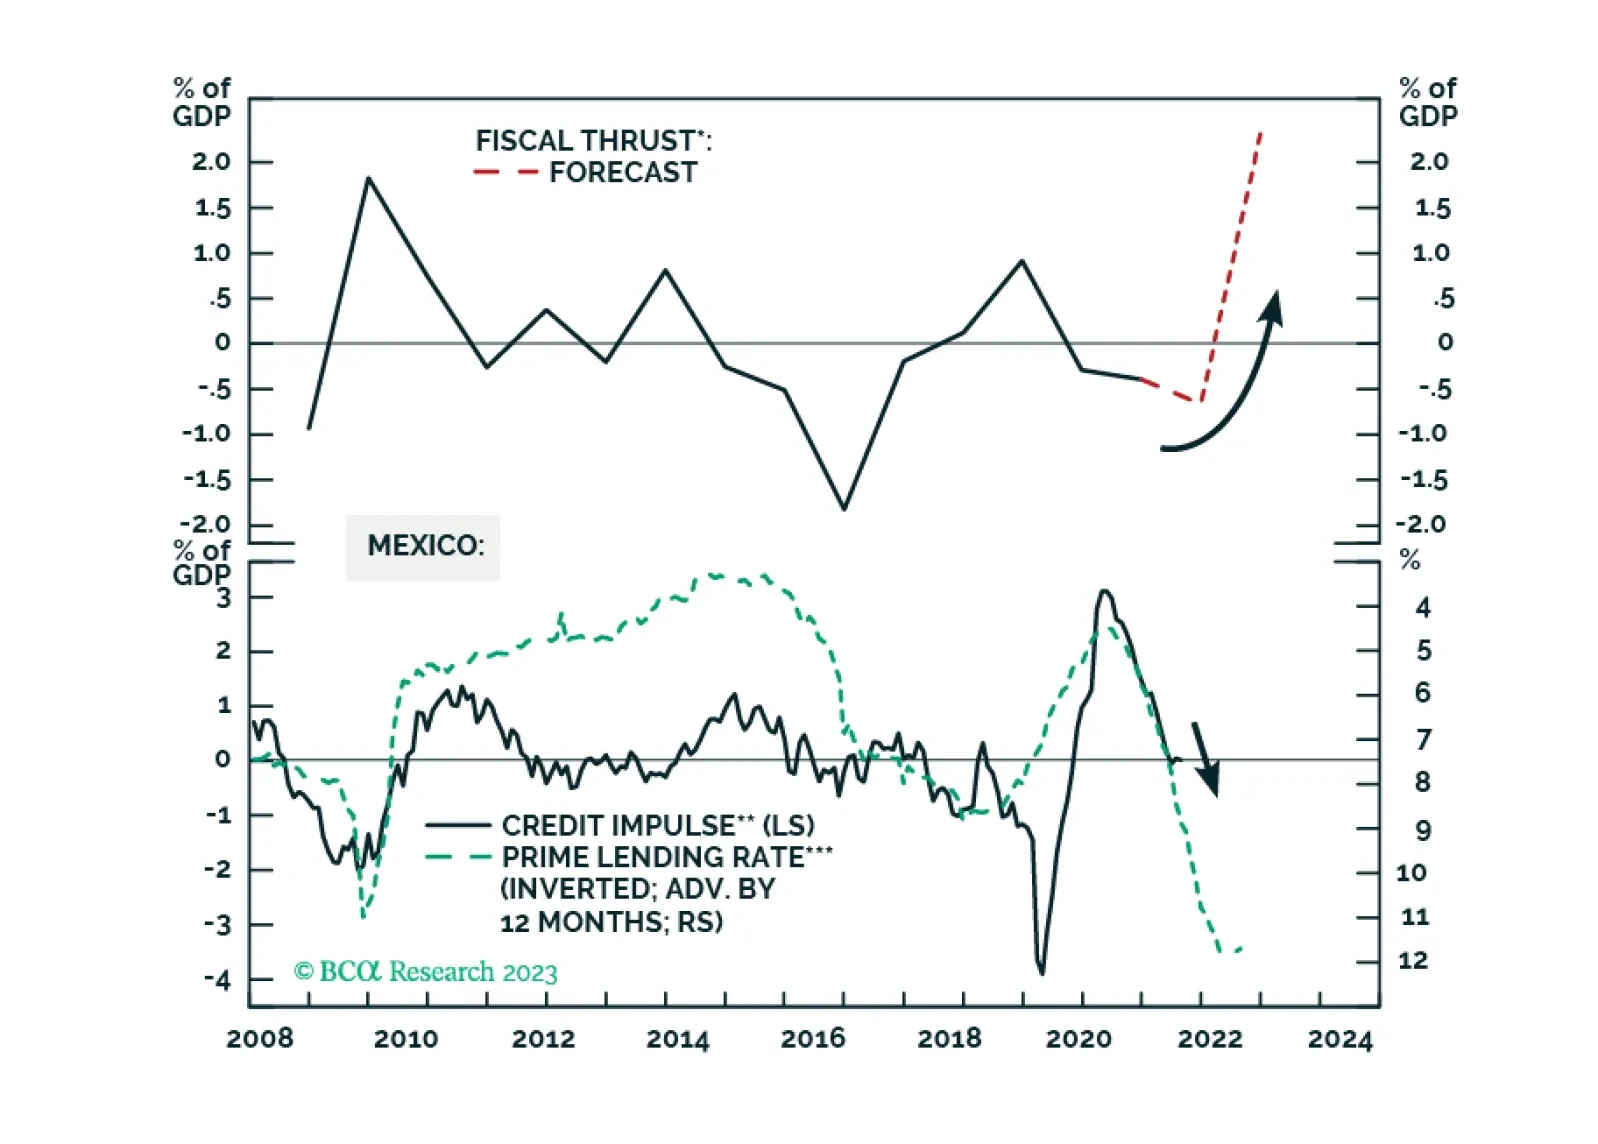
While Mexican markets will continue selling off in absolute terms, their recent underperformance versus their EM peers is a temporary setback in a cyclical and structural bull market. Domestic politics are evolving from stable to bullish: the new president will rule in a technocratic manner, respecting private sector interests. The Mexican economy will achieve a soft landing even if the US enters a recession.
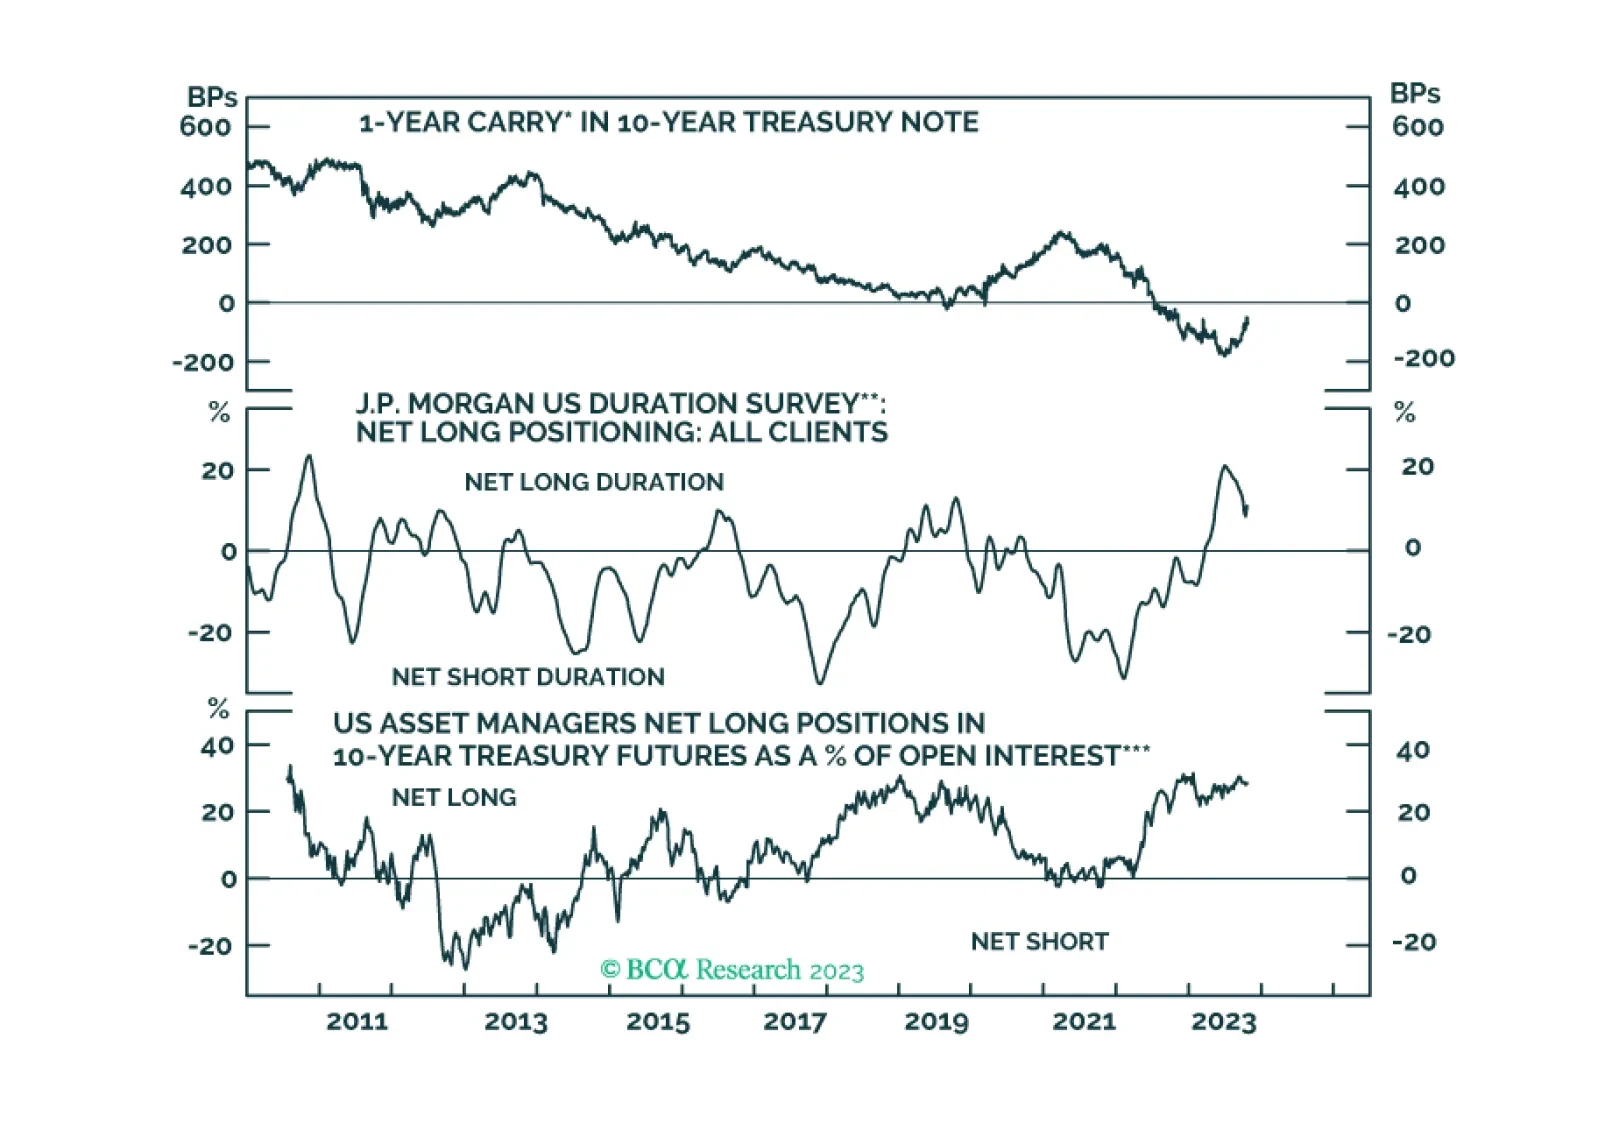
This week’s report contains an update on the Treasury curve’s recent bear-steepening trend and a look at different measures of long-maturity Treasury valuation.

The wall of maturities for Office and Multifamily Real Estate is upon us. The impact of rising interest rates is also being felt by Private Equity and Venture Capital. The difficulties faced by smaller US banks is providing further tailwinds to Direct Lenders. Hedge Funds will benefit from a more volatile backdrop over the next 1-2 years. Now is the time to resize Crisis Risk Offset portfolios.
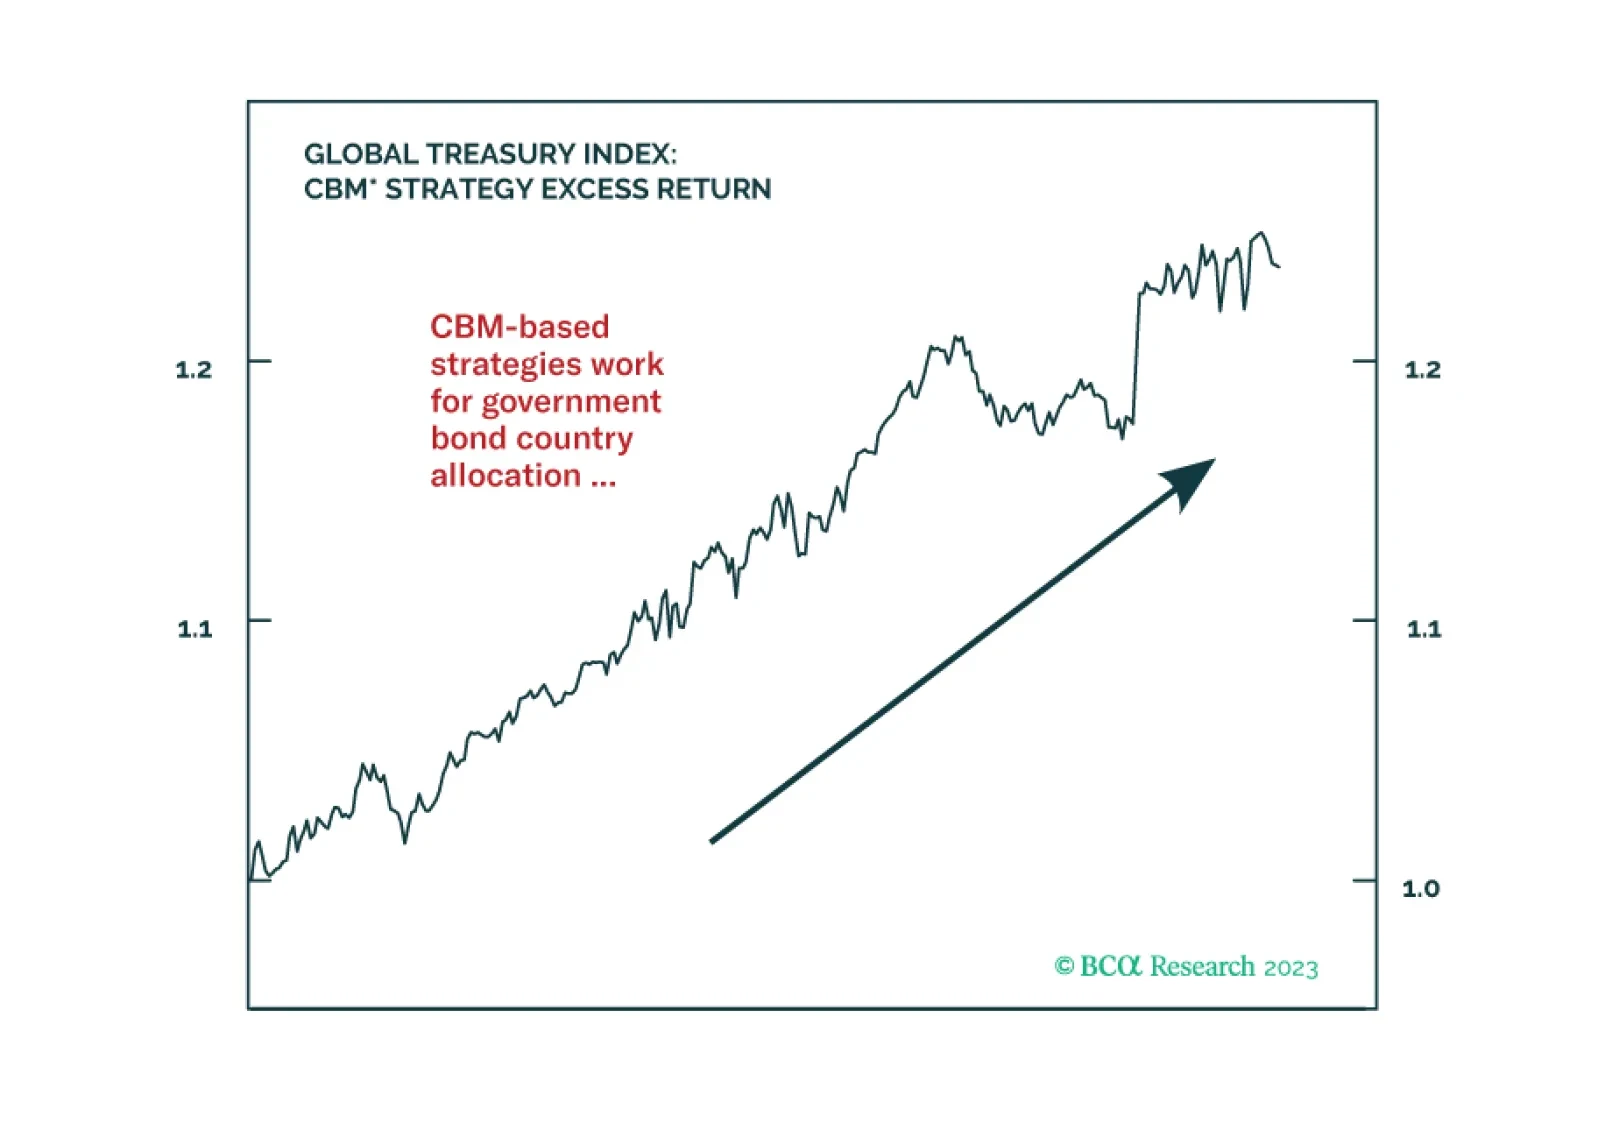
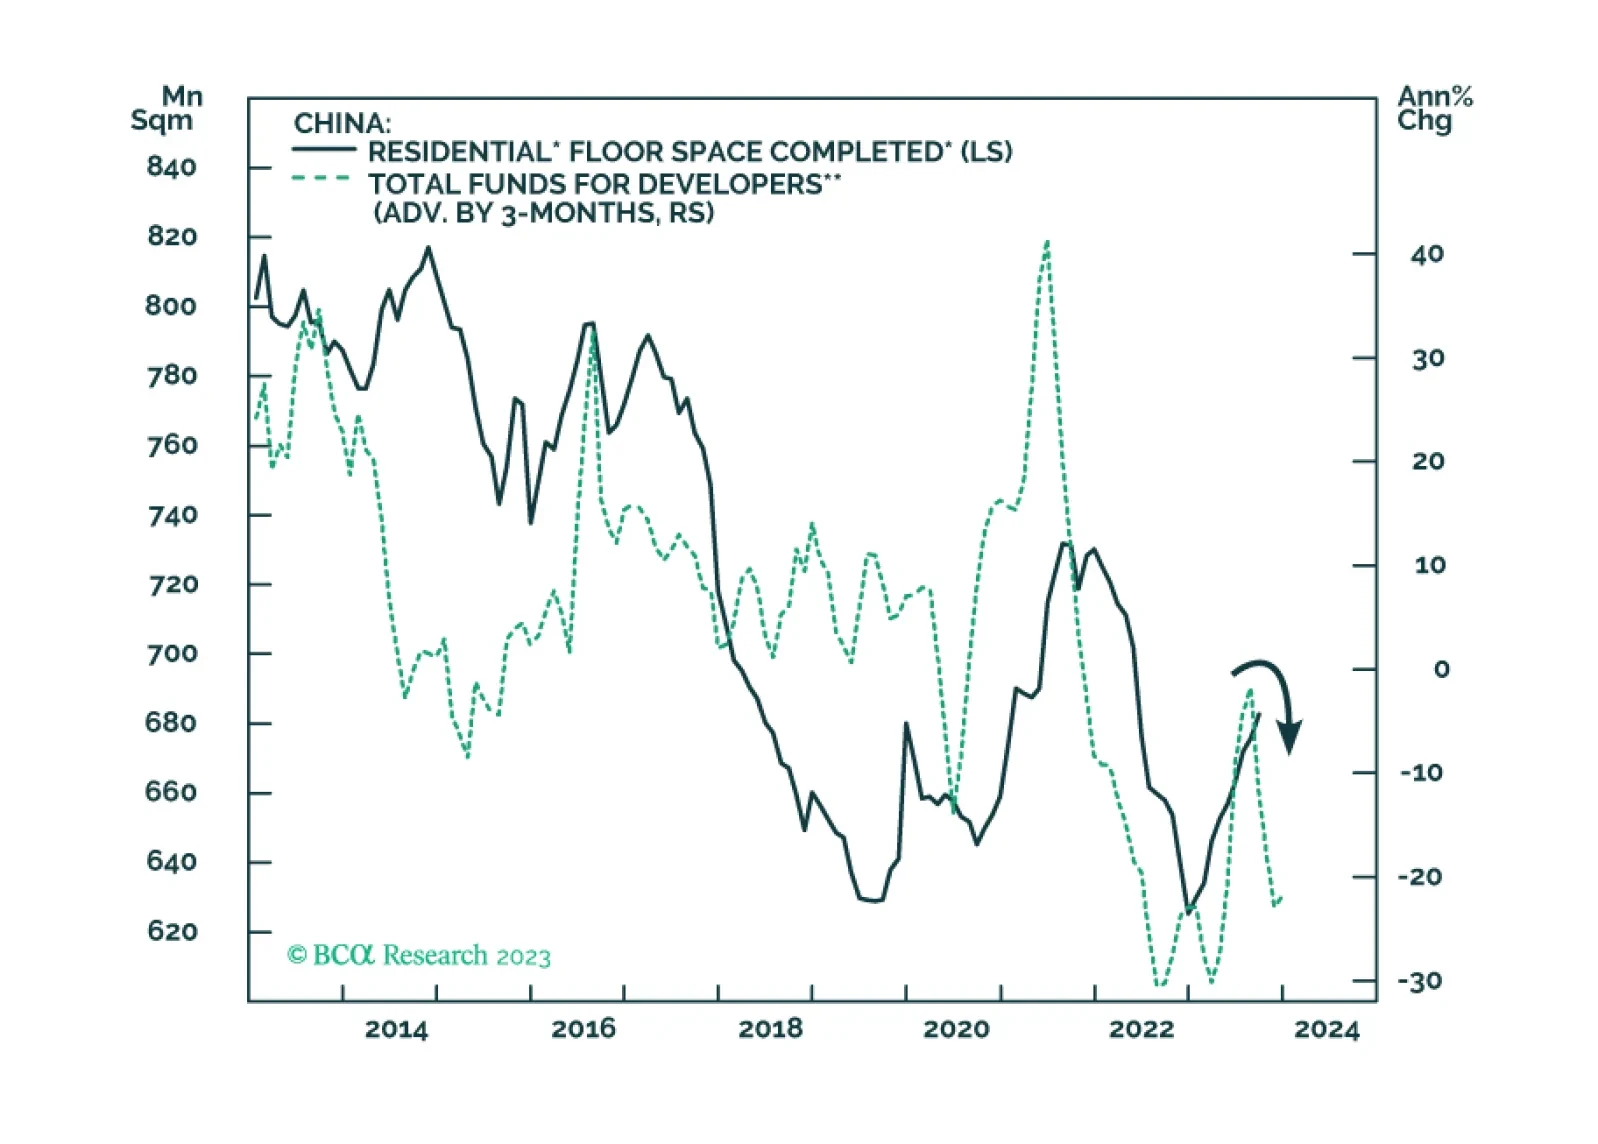
China’s economic growth will stagnate, at best, rather than revive. Lower valuations of Chinese equities are justified, and share prices have more downside. The RMB will continue to depreciate versus the US dollar.
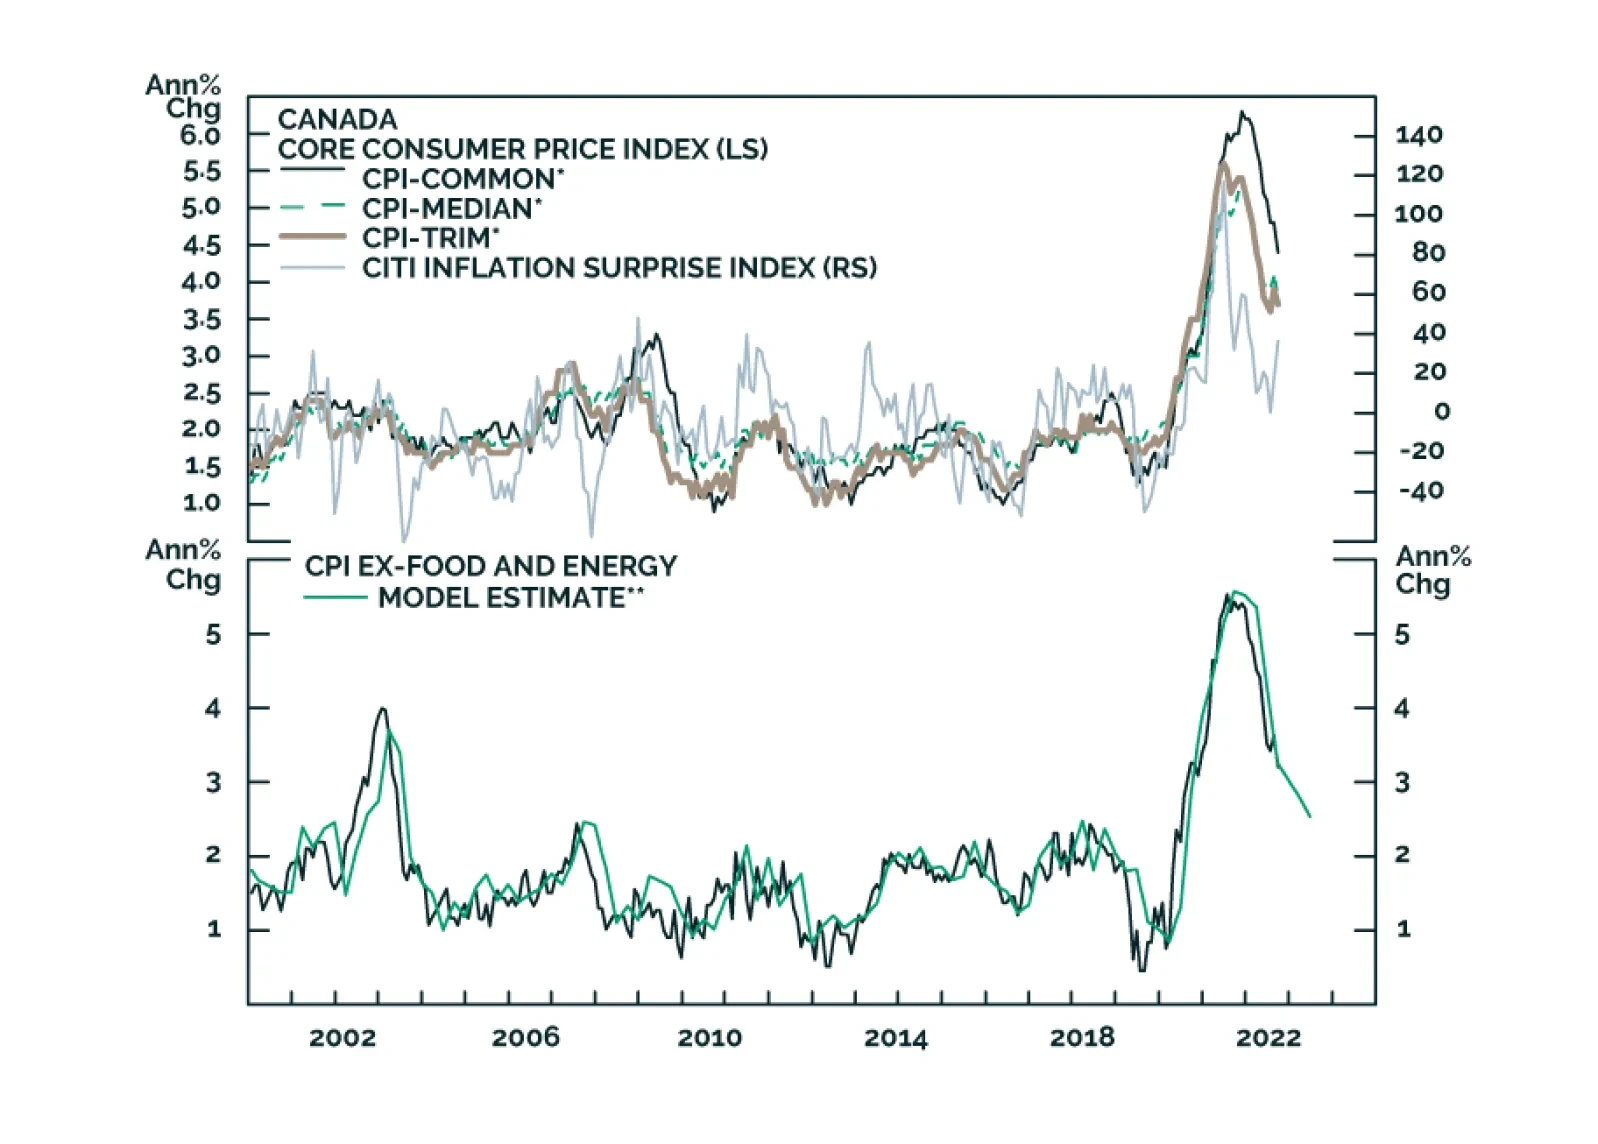
In this insight, we look at whether the recent data justifies a shift by the BoC, and some potential trades.