Skip to main content

Latest from BCA Research
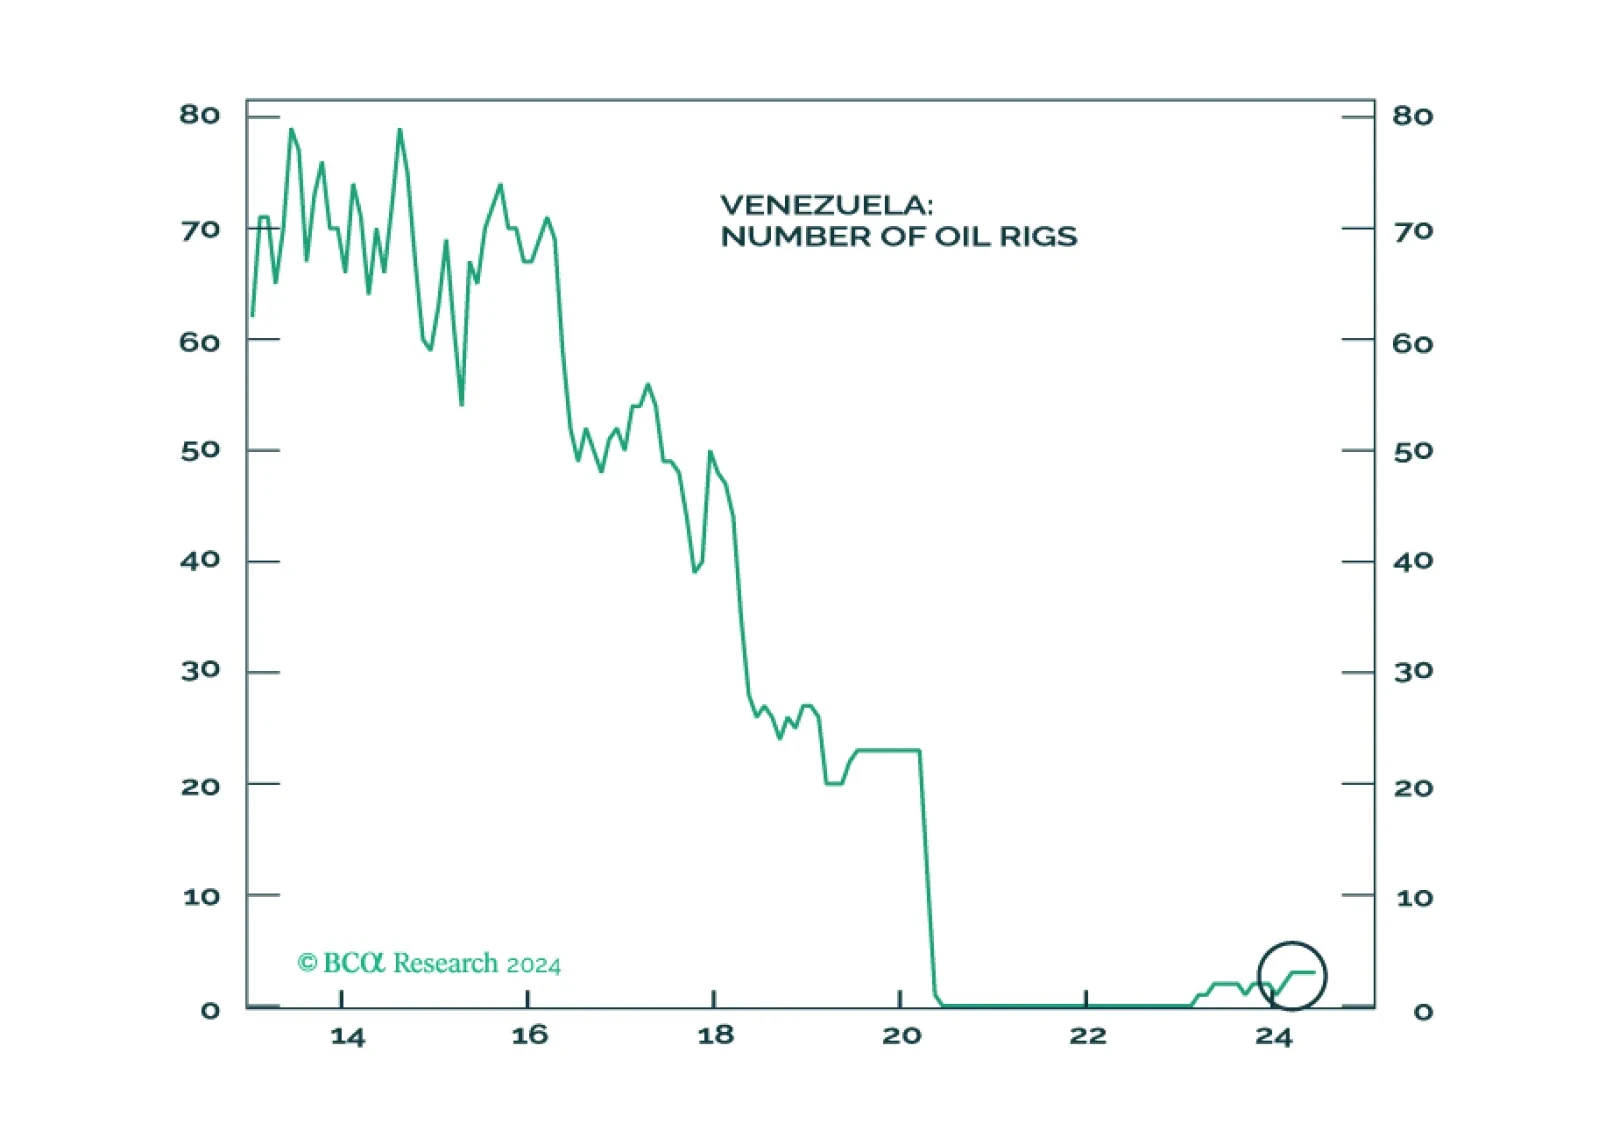
Special Report Oil markets will not be impacted by Venezuela in the near term, but by shocks from the Middle East. Maduro’s ability to stay in power in the short-term removes an avenue of oil supply relief. The same avenue is cut off if Trump is reelected. Geopolitical shocks in Venezuela could present tactical buying opportunities for Chile, Peru, and Colombia.
Bank Credit Analyst
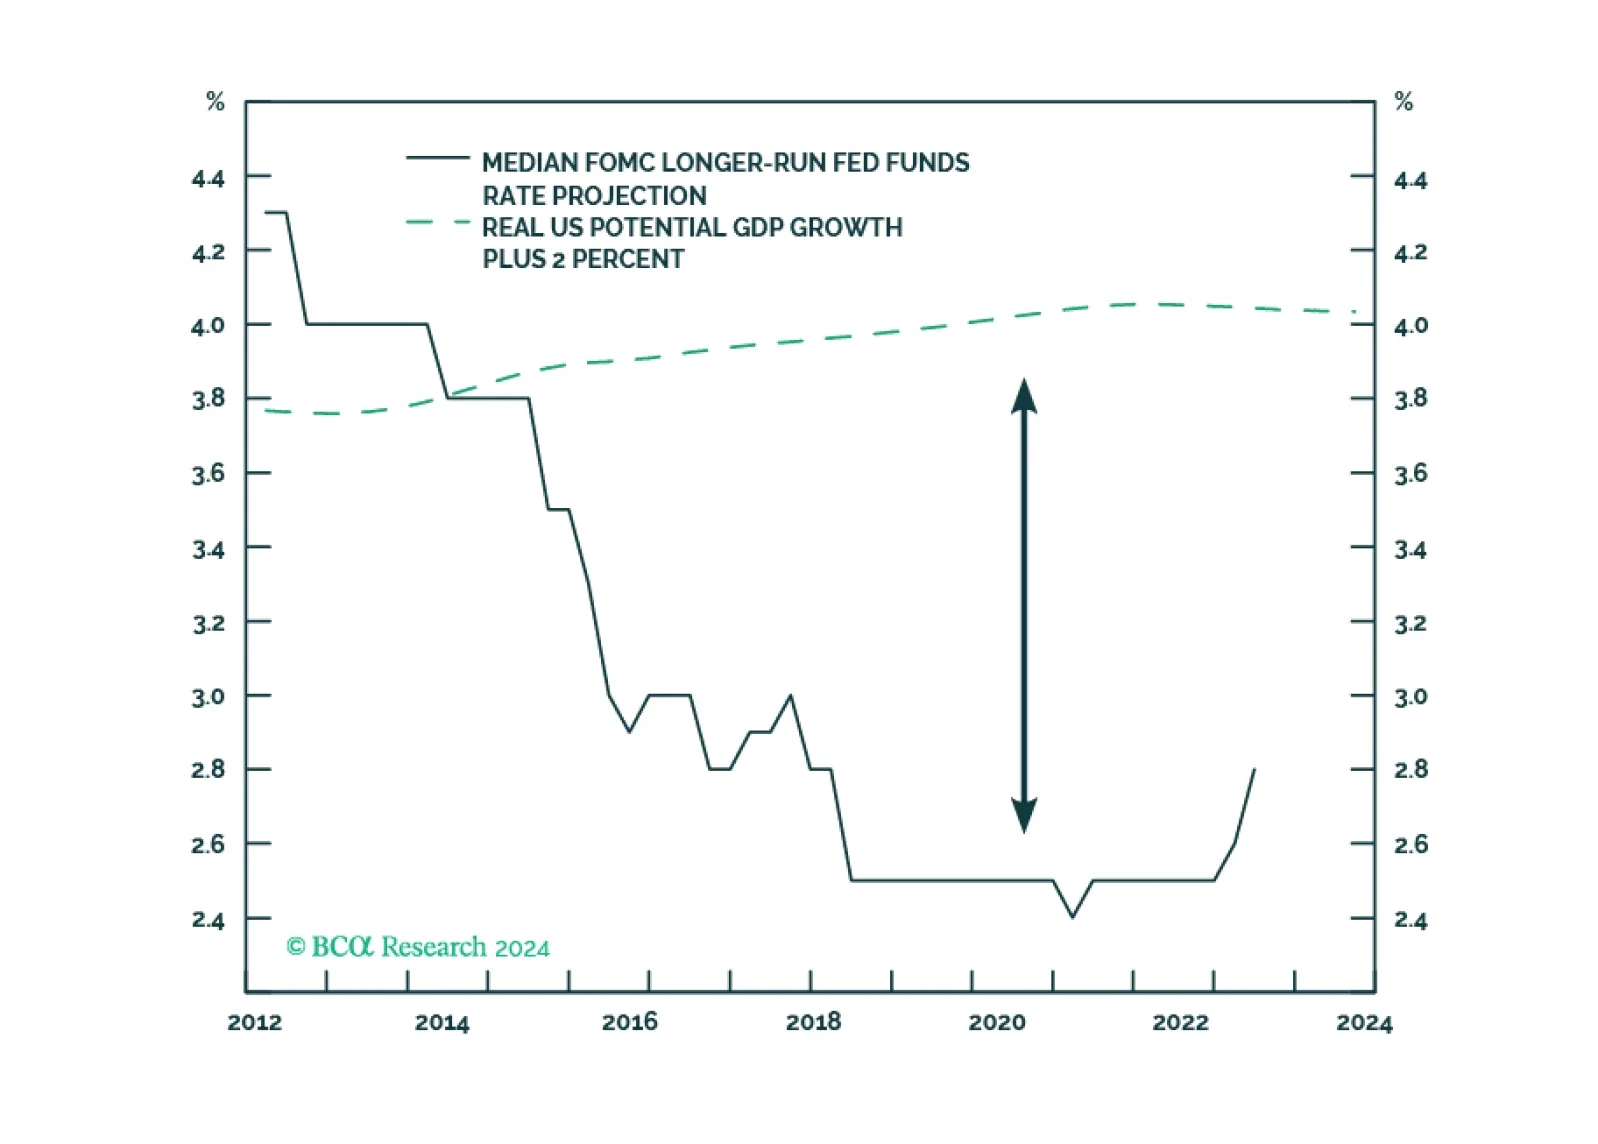
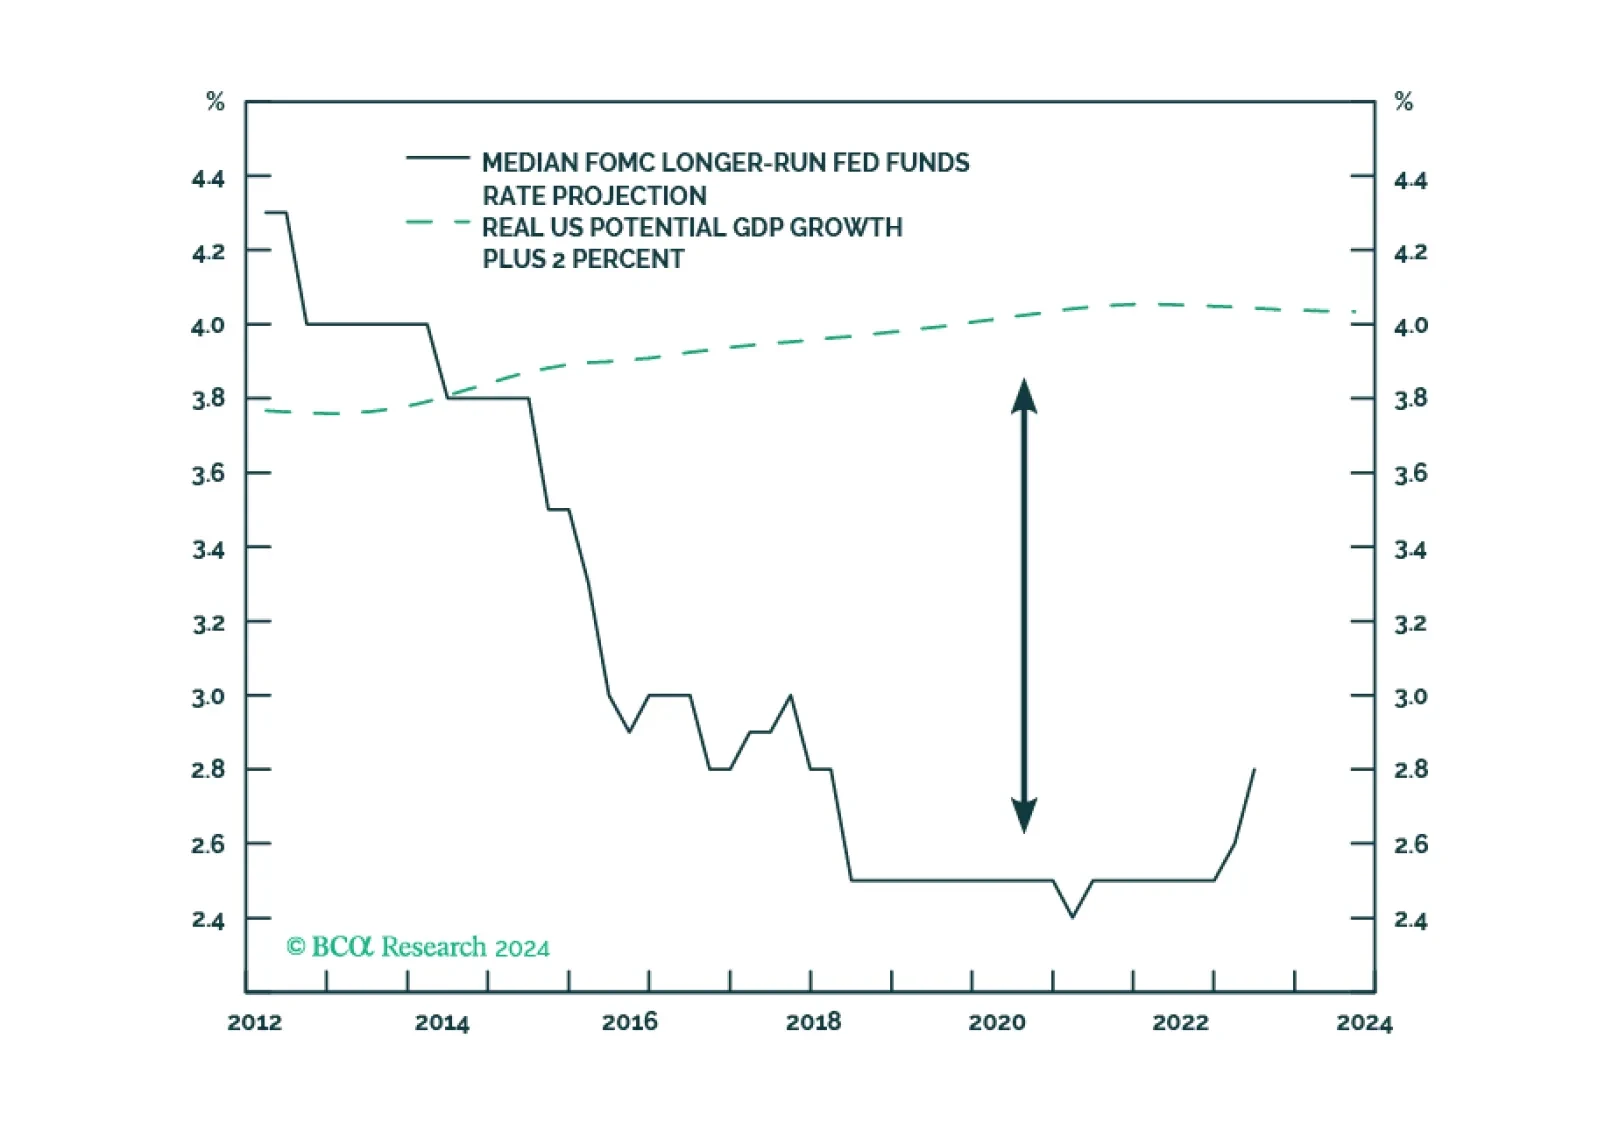
Special Report In this Special Report, Jonathan LaBerge of The Bank Credit Analyst argues that the Fed should abandon the framework changes that it made in 2020, both to its inflation and employment objectives. If “structural dovishness” is made a permanent feature of Fed policy, investors can expect more frequent booms and busts in financial markets, and higher odds of future inflation overshoots.
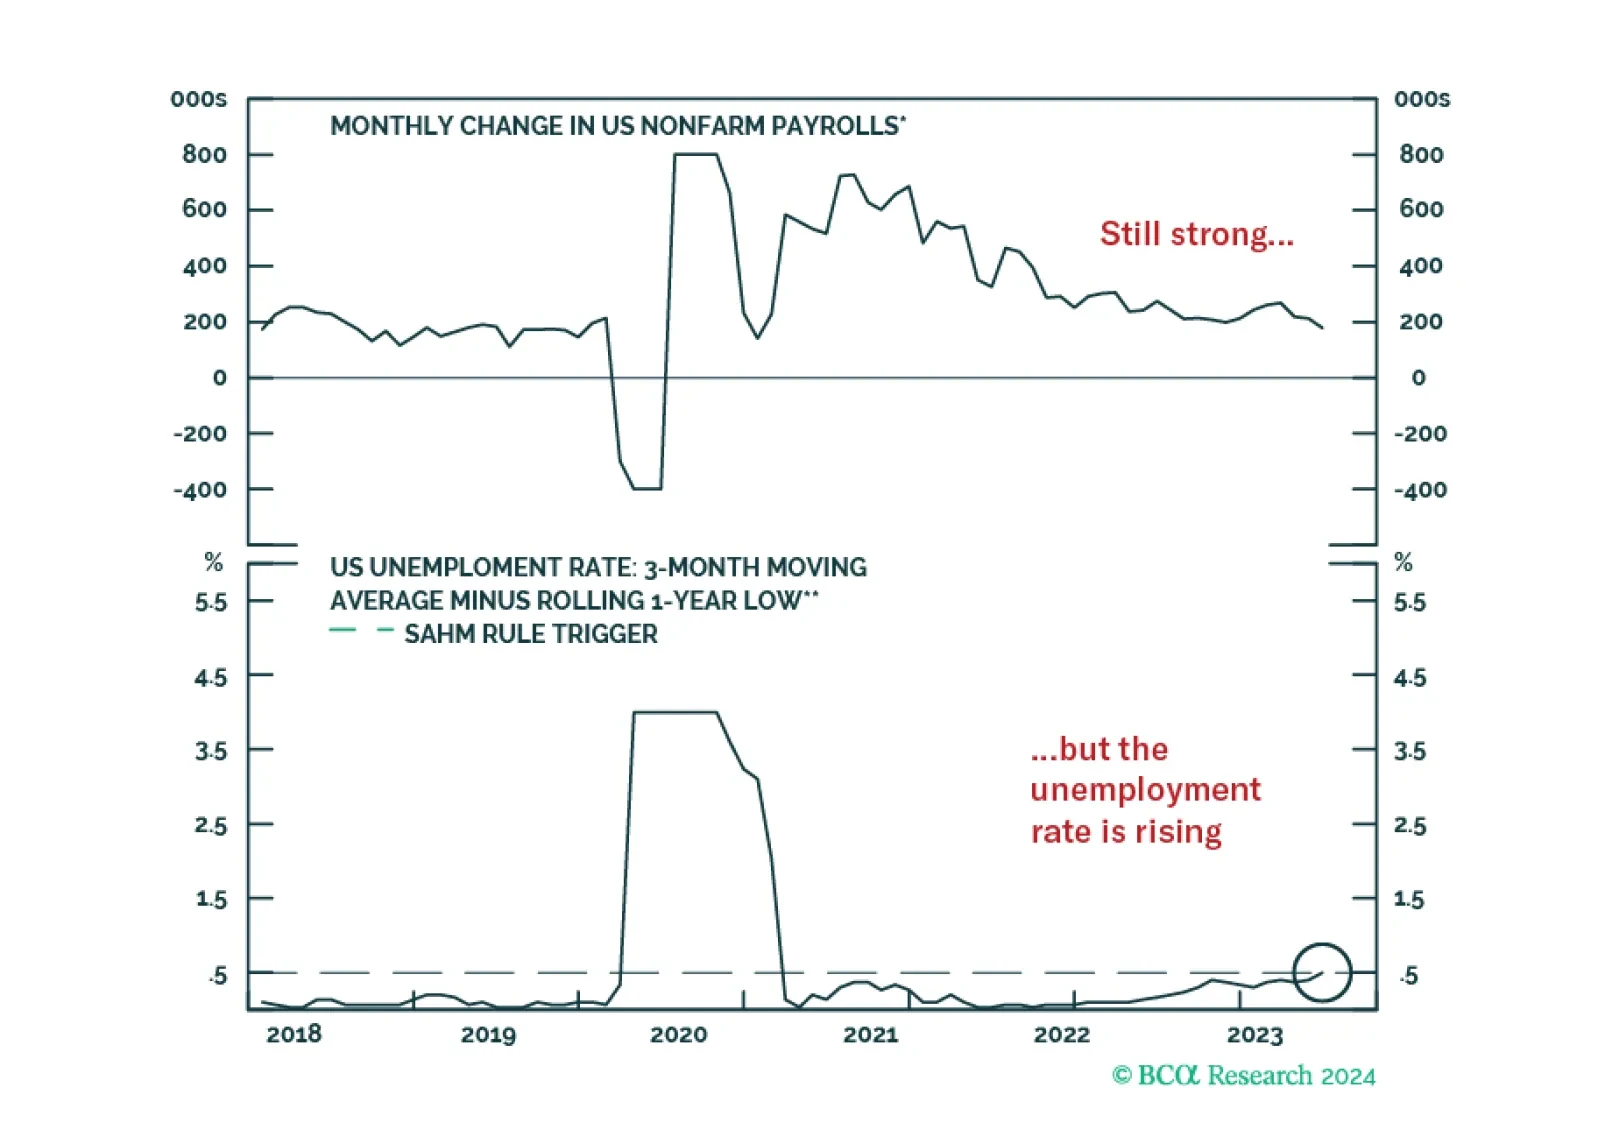
Bank Credit Analyst In Section I, we note that the US labor market is turning, and that the economy is indeed slowing to a recessionary tipping point. Disinflation continues, but not at a pace that would allow the Fed to cut aggressively outside of the context of a recession. We continue to expect that Donald Trump will win in November, and trade policy under a second Trump presidency represents a significant risk for investors. We continue to recommend conservative positioning over a 6-12 month time horizon. In Section II, we argue that the Fed should abandon the framework changes that it made in 2020, both to its inflation and employment objectives. If “structural dovishness” is made a permanent feature of Fed policy, investors can expect more frequent booms and busts in financial markets, and higher odds of future inflation overshoots.
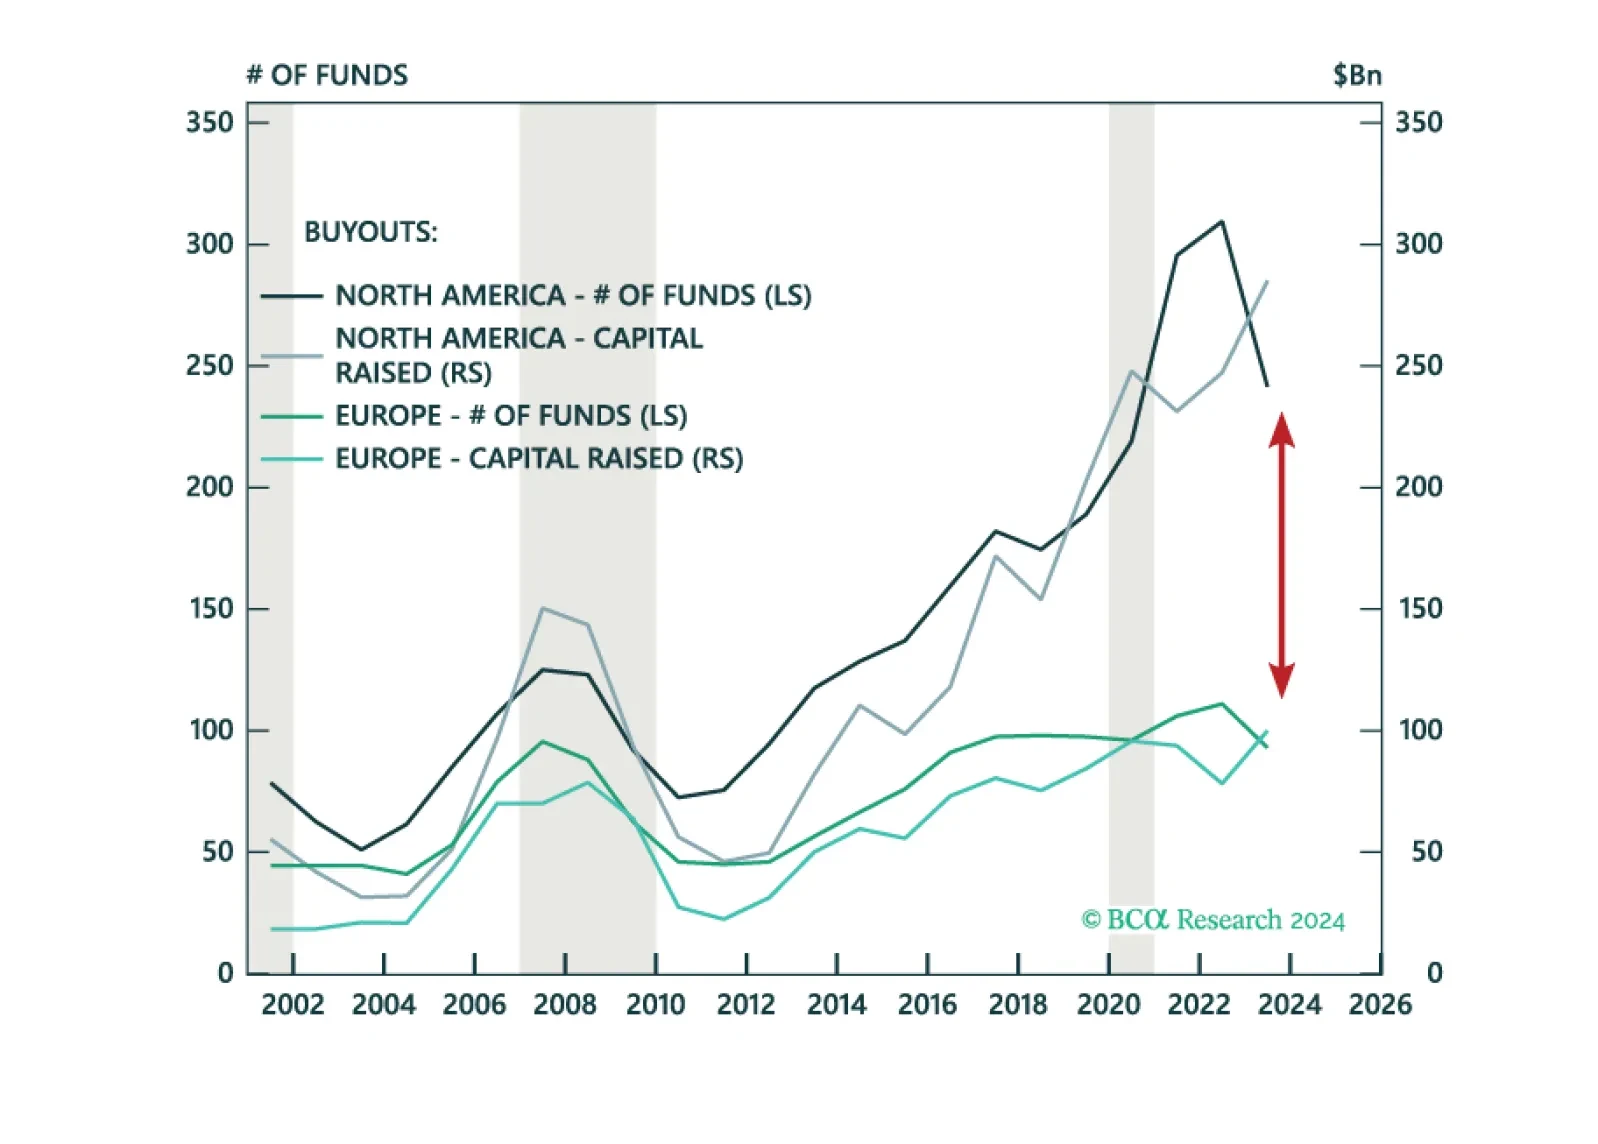
We are growing positive on Growth assets with recession expectations increasing our optimism on entry points. Equities are led by APAC Private Equity, North America Venture Capital, and Europe Buyouts. Our outlook continues to improve on CRE within the Inflation & Diversification bucket while we are underweight Multi-Strategy amongst Hedge Funds. We maintain an overweight to Senior Direct Lending for Income with a preference for North America.
After this morning’s jobless claims number, we have now seen enough deterioration in our preferred labor market indicators to increase portfolio duration from “at benchmark” to “above benchmark”.
This report provides our framework for interpreting the messages from last week’s Third Plenum, and the potential implications for the economy and investors.
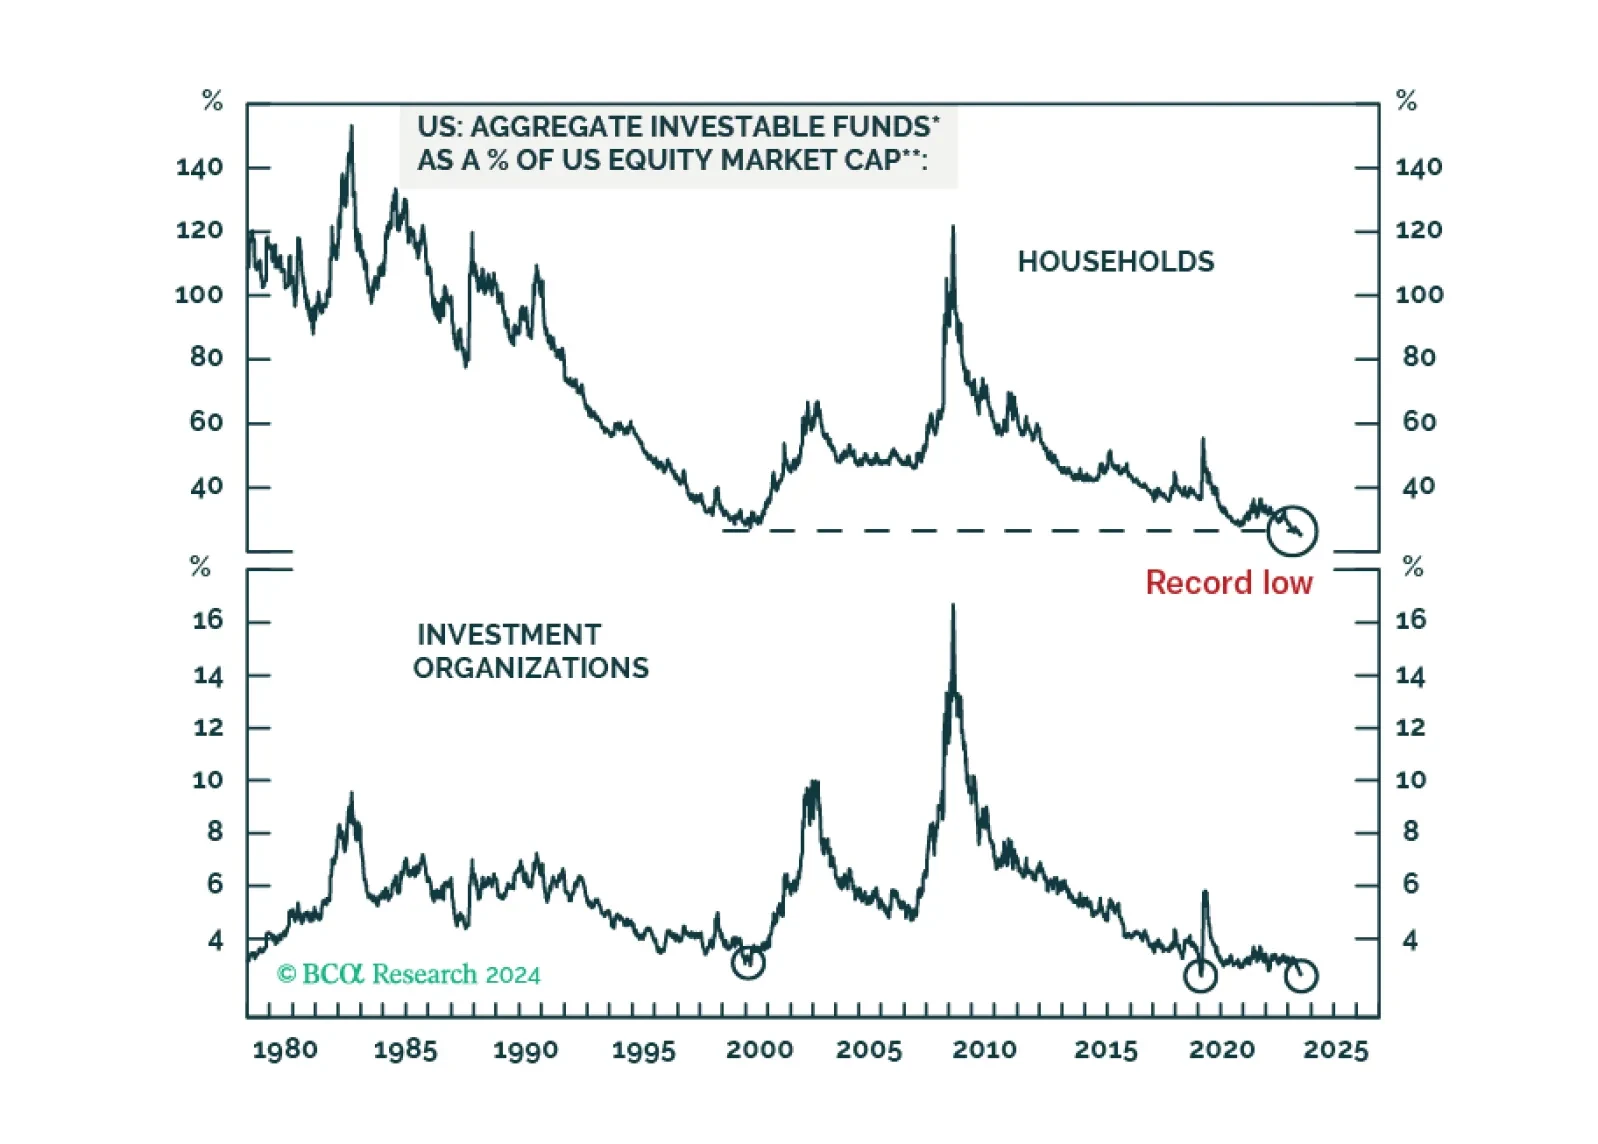
“Cash on the sidelines” as a share of the US equity market cap has declined to a record low. This is true for investable funds of both households and investment firms. Hence, there is little firepower left to sustain the equity rally.
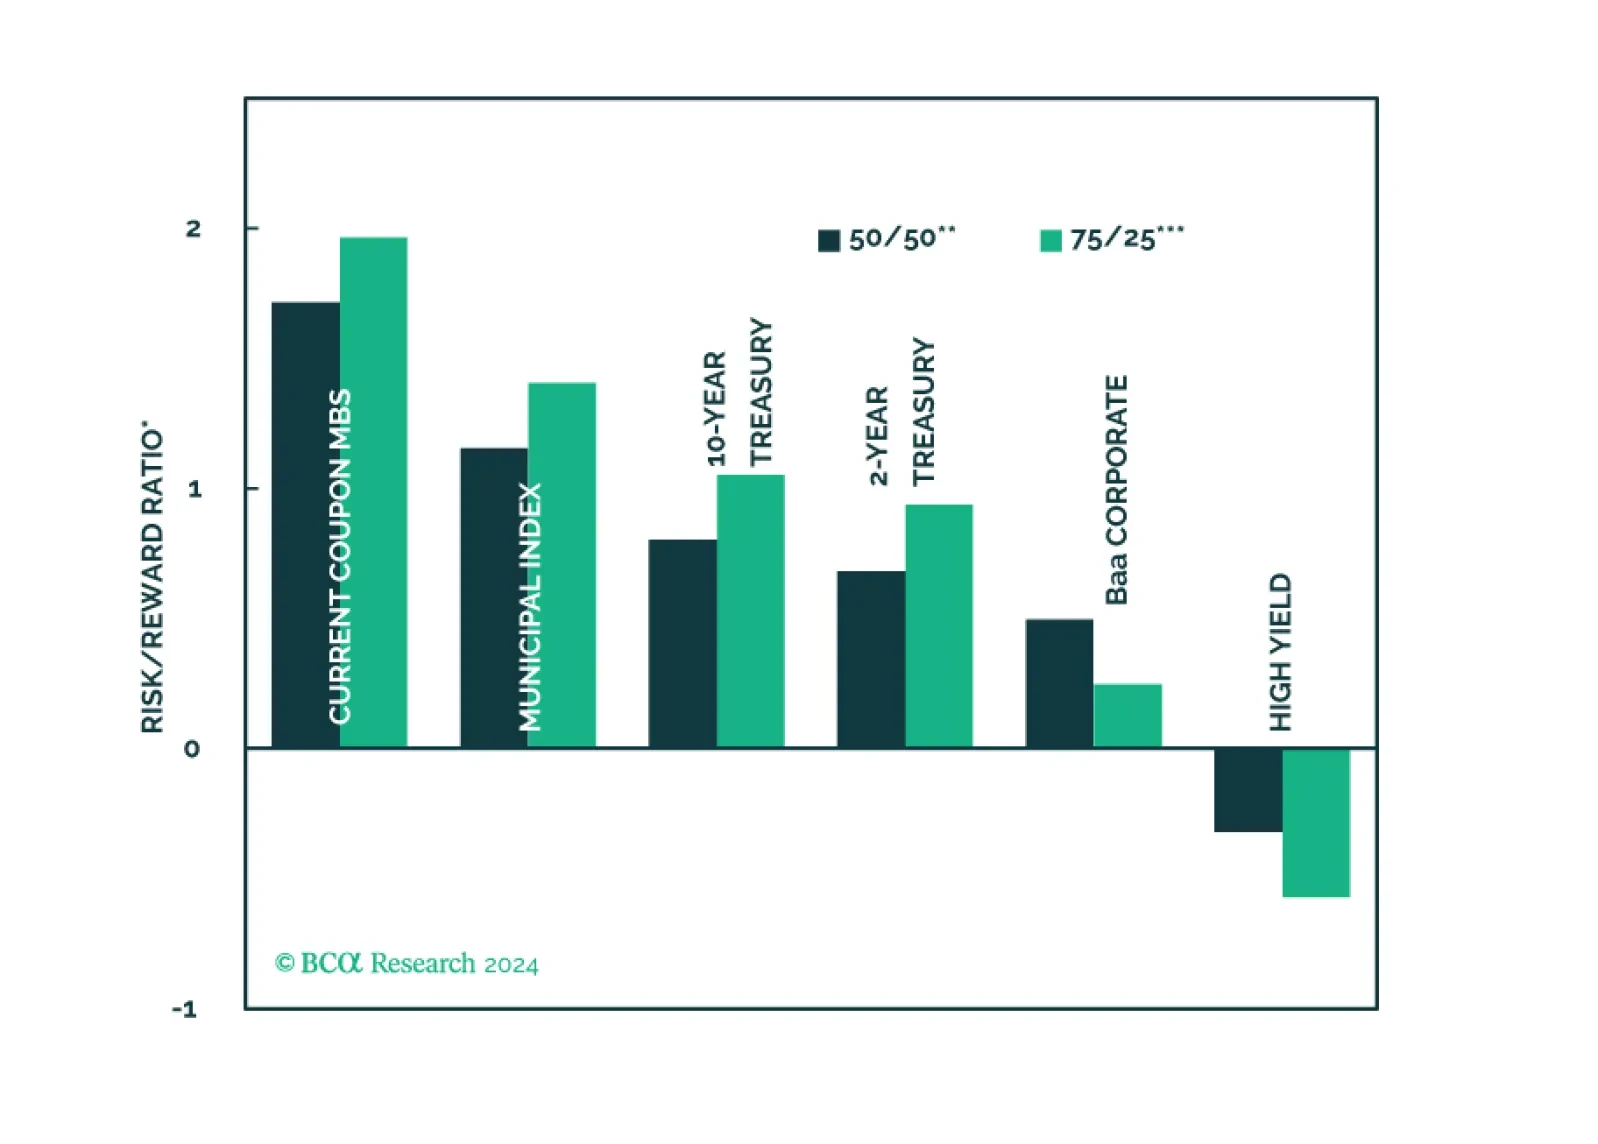
We calculate expected returns for several different US fixed income sectors with a focus on how municipal bonds stack up against the investment alternatives.
Special Report Strong broad-based earnings growth could prolong a bull market but won’t stave off a recession, as it will emanate from struggling small businesses and less affluent consumers. Banks’ traditional business is under pressure, but capital markets activity is rebounding sharply. Recent rotation is profit-taking, but cheap areas of the market will outperform in relative terms in a downturn.