Latest from BCA Research
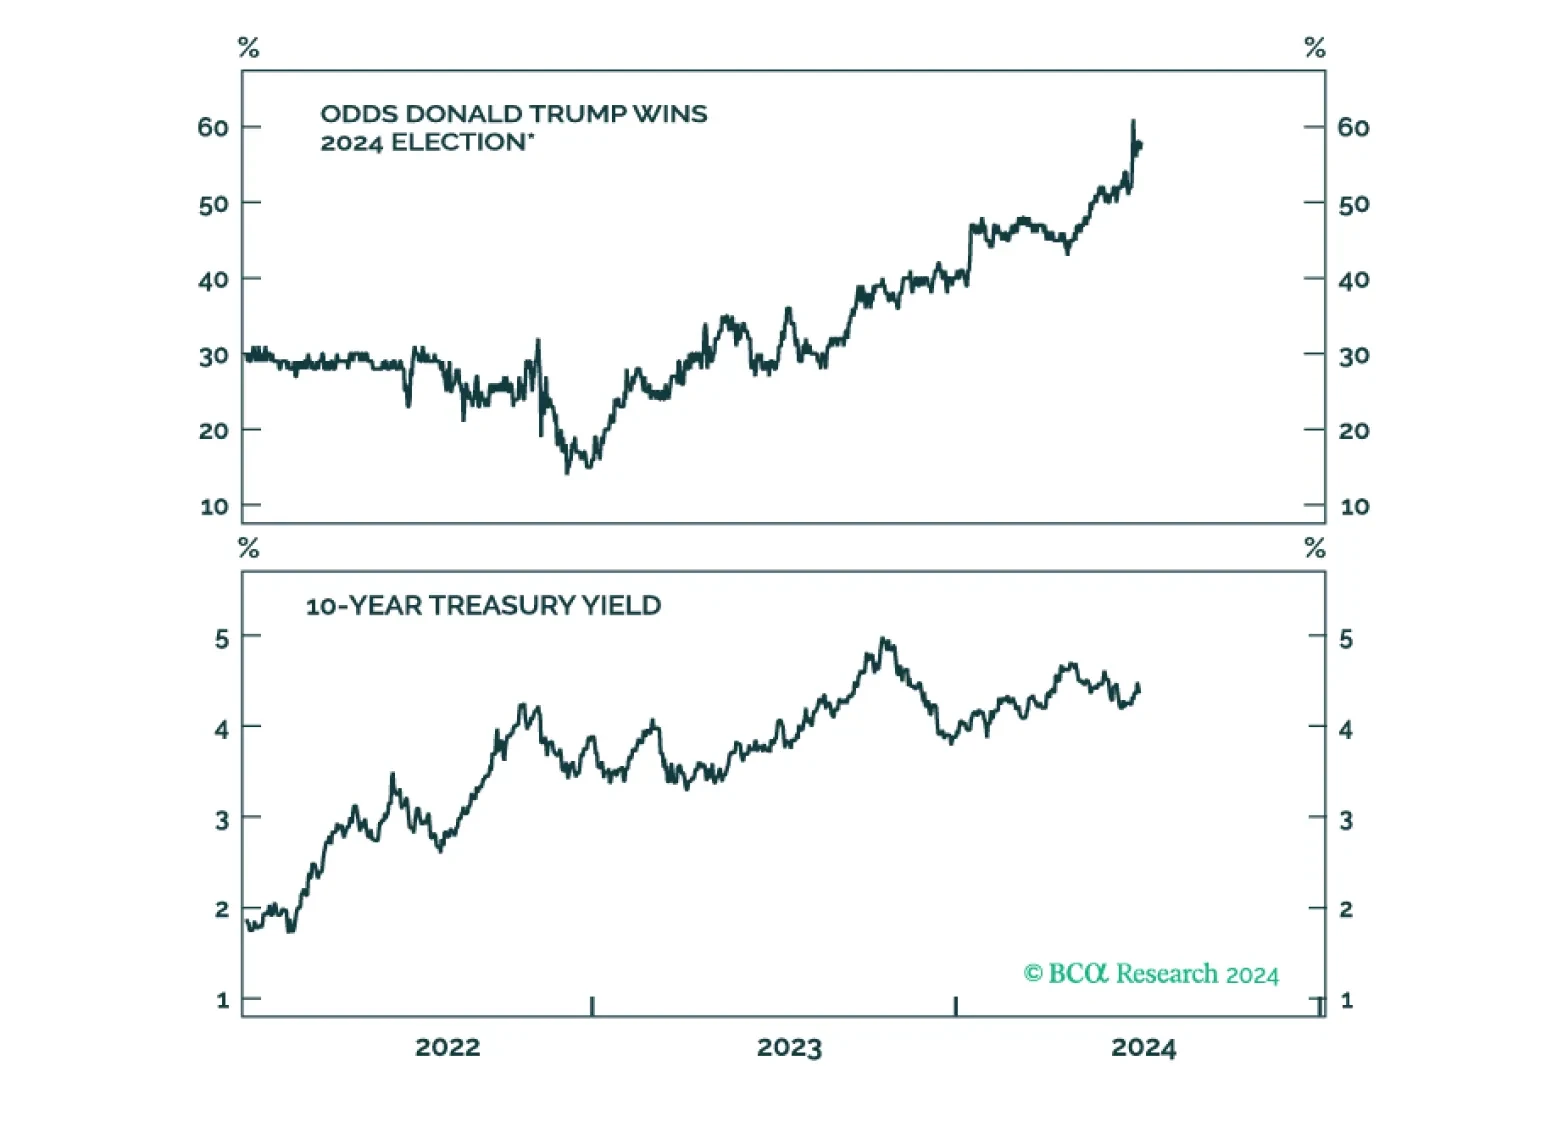
Our labor market indicators have softened meaningfully during the past month but aren’t yet signaling an imminent recession. That said, the Fed can no longer ignore the labor market with the unemployment rate above 4% and rising.

The new Labour government will have flexibility to respond to macro shocks, which is positive for the UK in general, namely GBP-EUR, and also gilts in absolute terms. But over the long run, tax hikes will likely surprise to the upside, which poses a risk to corporate earnings.
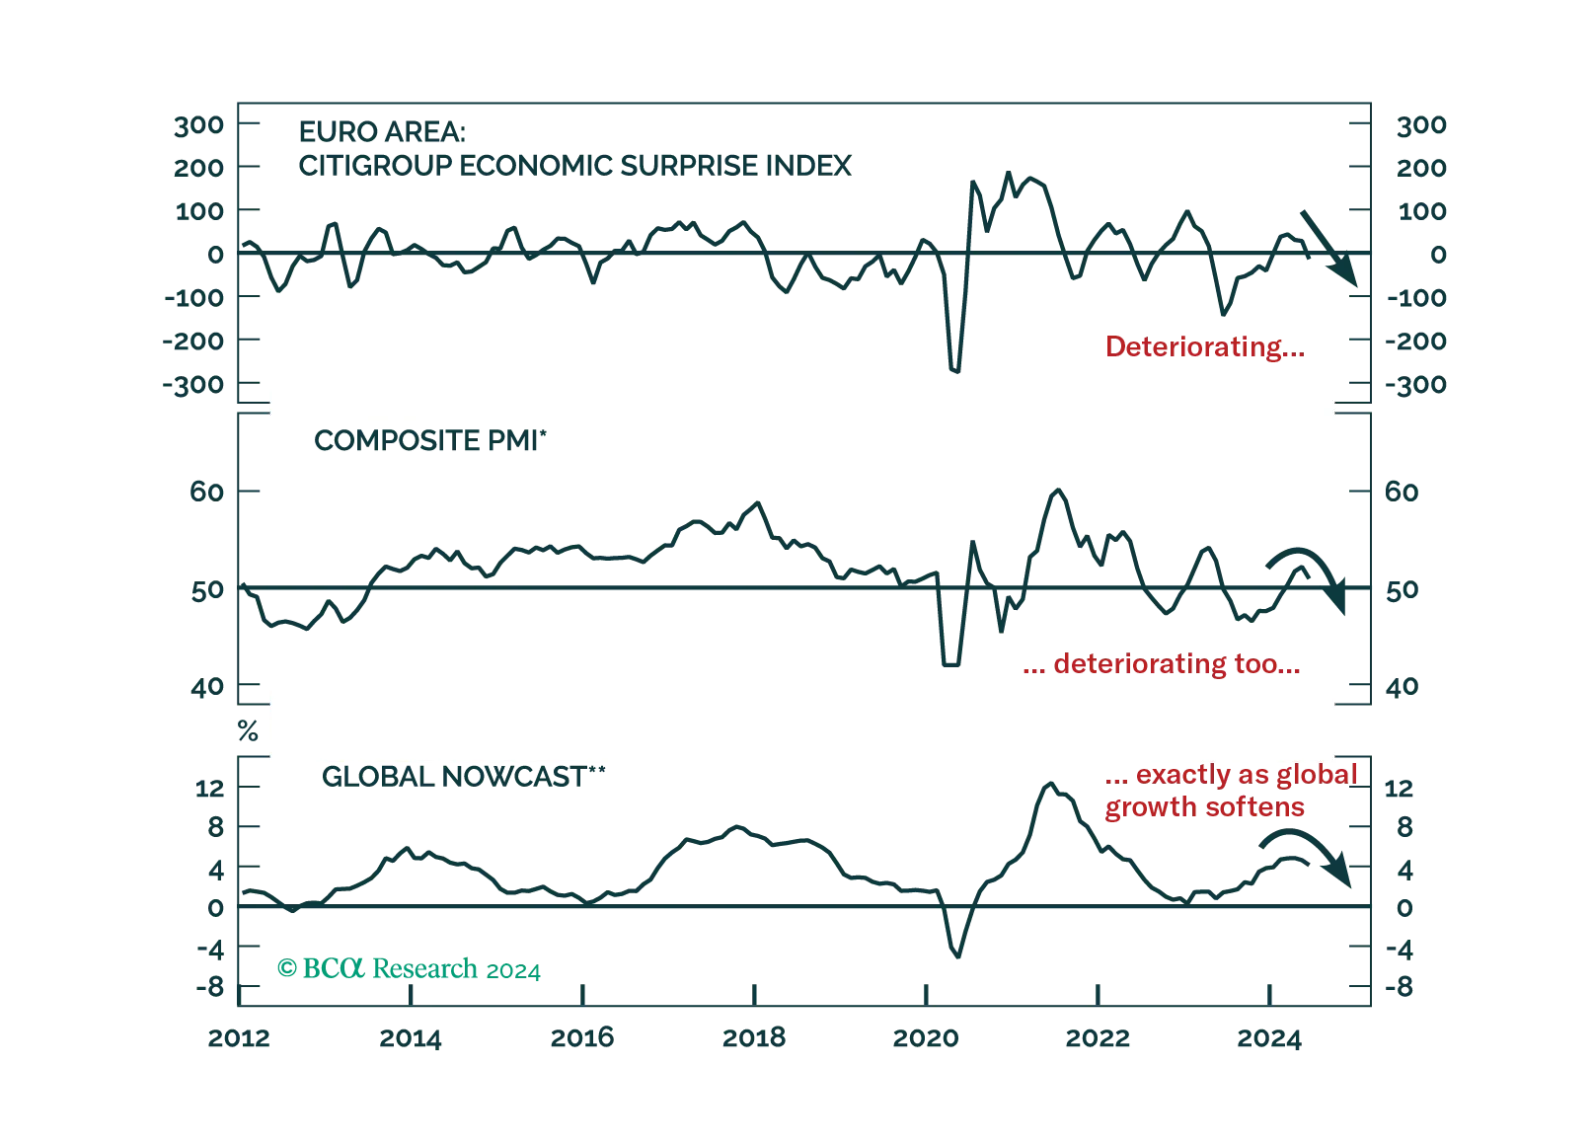
Does the incipient slowdown in European data herald a soft landing and a goldilocks period for equities? We have our doubts.
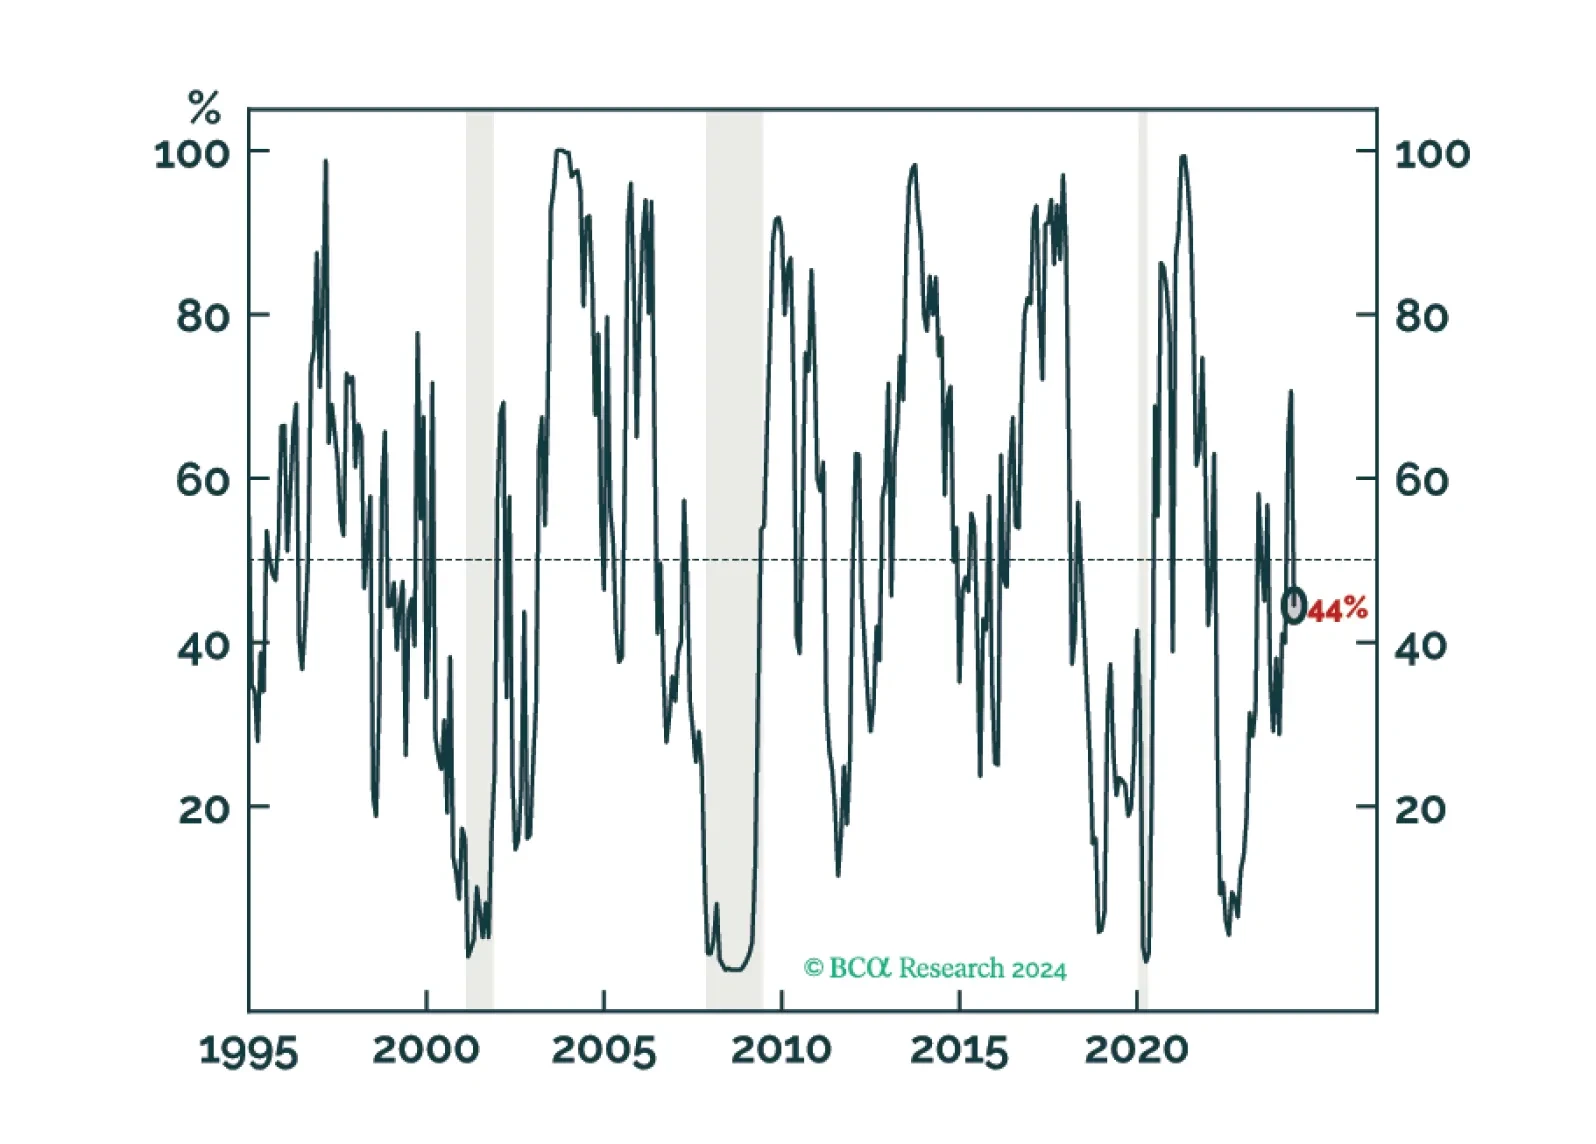
Global Equity Score drops to neutral. Sector model upgrades Tech and Real Estate, while downgrading Industrials and Base Materials.
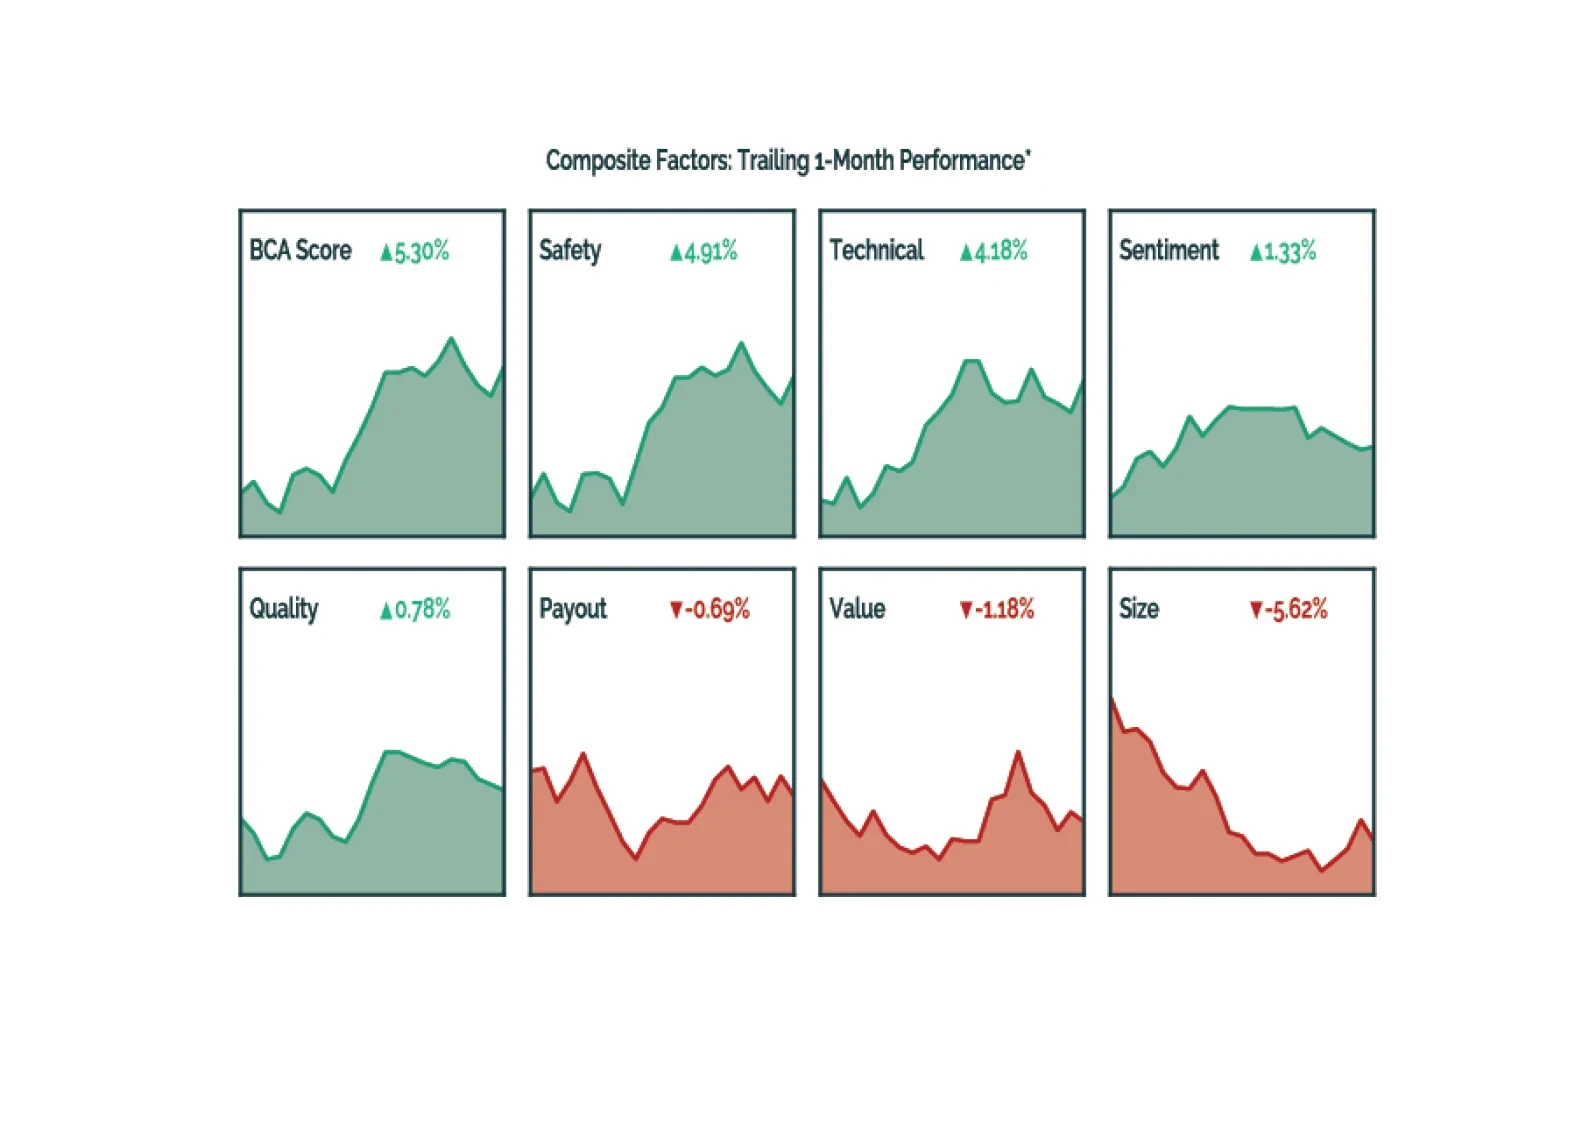
US High-Quality Strategy outperforms on the back of the BCA Score. Safety and Technicals lead the factor landscape, and while small caps struggled, the SMID portfolio also outperforms.
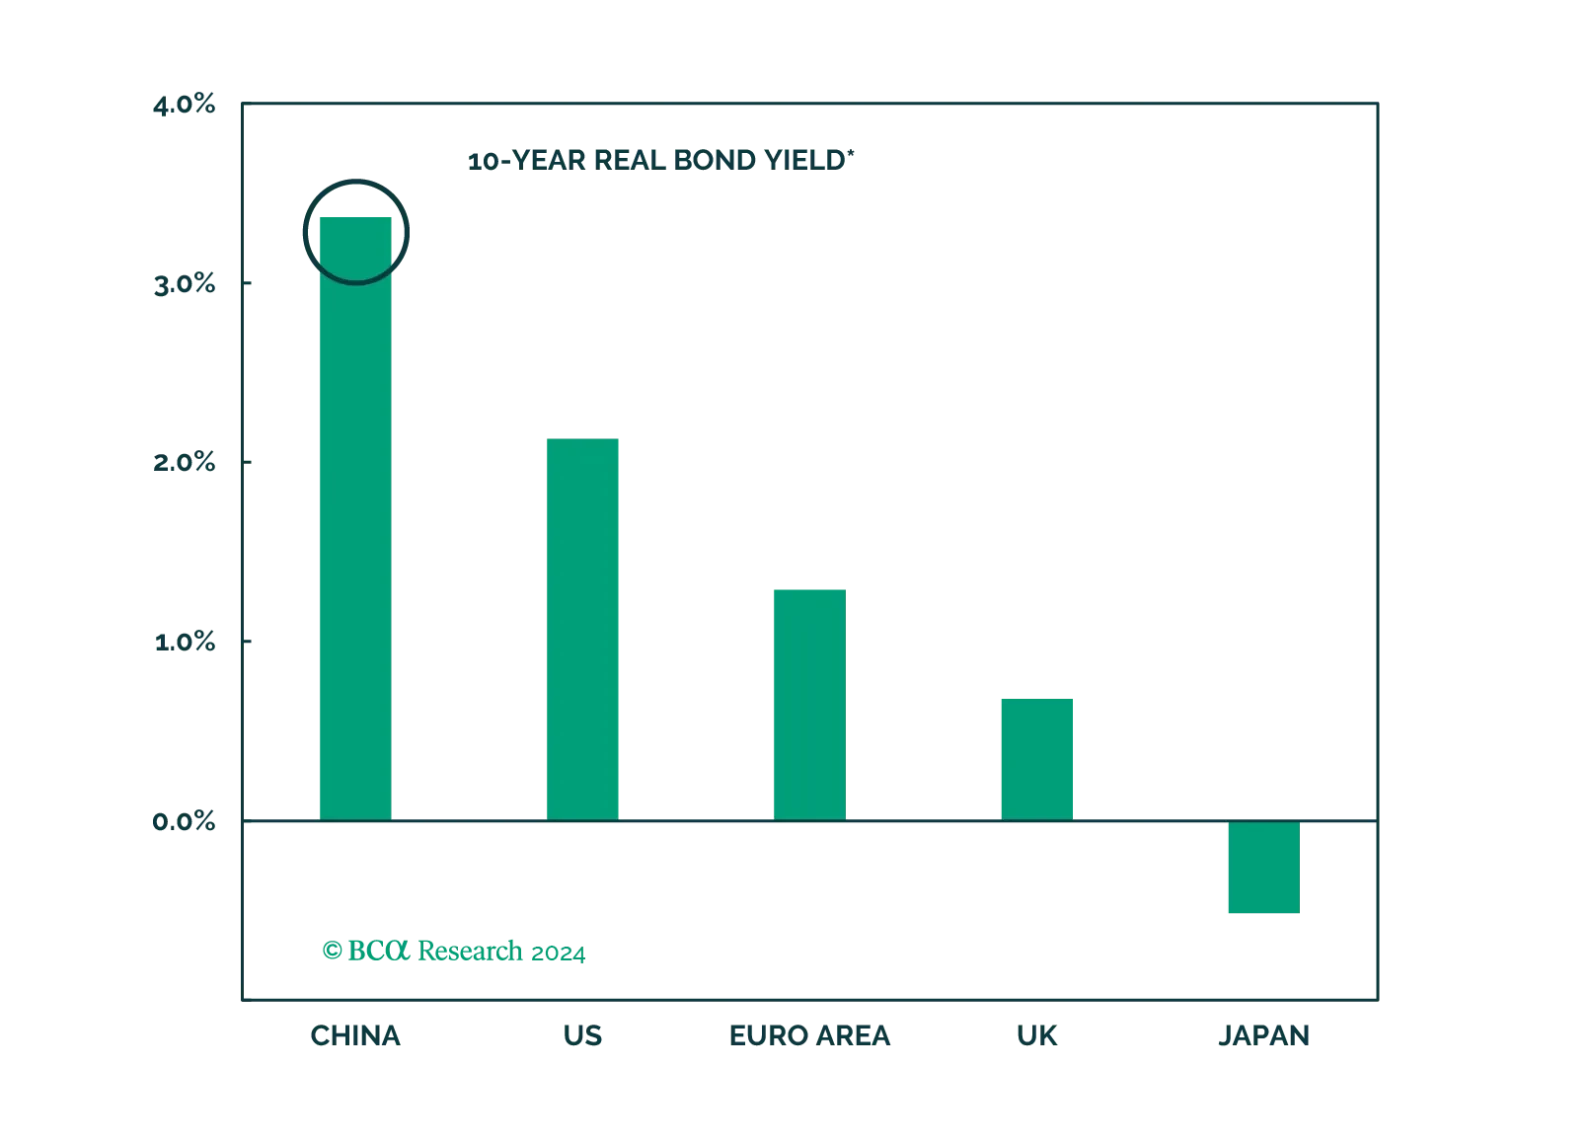
The PBoC appears increasingly uncomfortable with the rapid decline in the Chinese government bond yields. While the PBoC will succeed in temporarily curbing investors’ enthusiasm for bonds, the central bank will be unwilling to raise interest rates and unable to intervene in the bond market in any meaningful and lasting way.

We explain how to distinguish between ‘good’, ‘bad’ and ‘ugly’ unemployment, why bad unemployment is a much better gauge of the jobs market than headline unemployment, and what this means for the tactical positioning in bonds and stocks. Plus: base metals (XBM) have already sold off sharply, so take profits in the short position and open a tactical overweight in global materials (MXI).
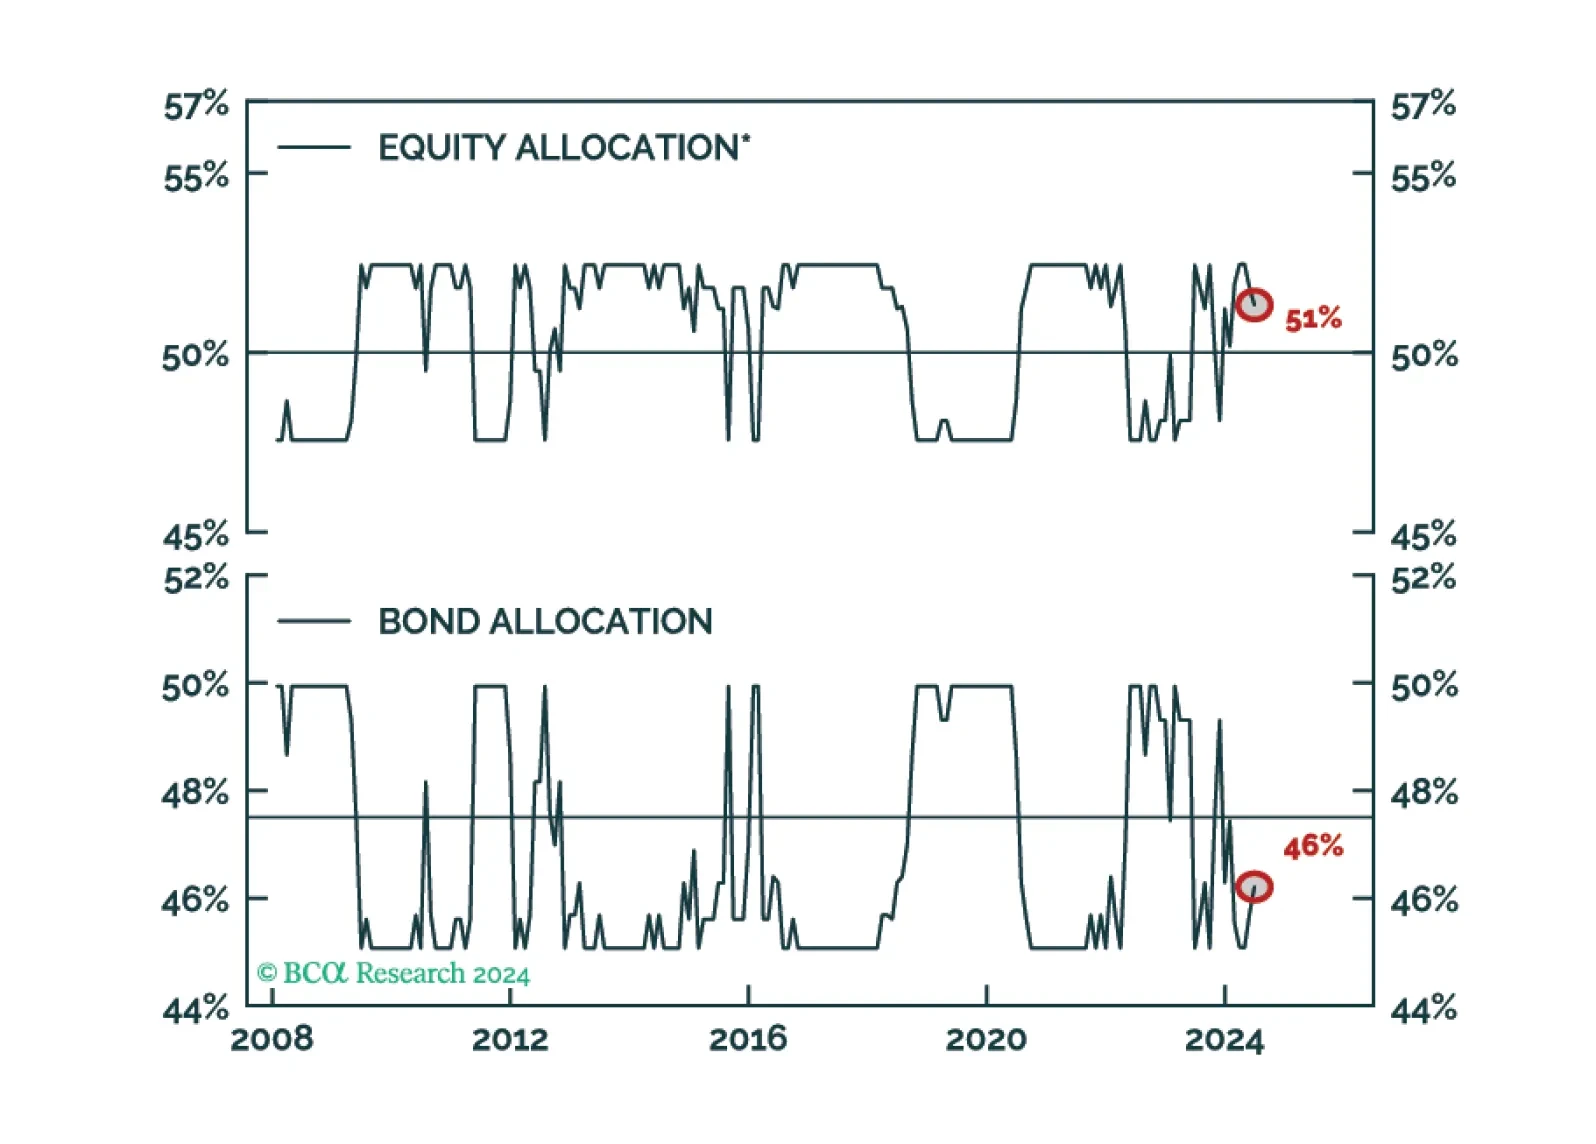
At the asset class level, the GAA Quant model is overweight equities, underweight bonds, and neutral cash.
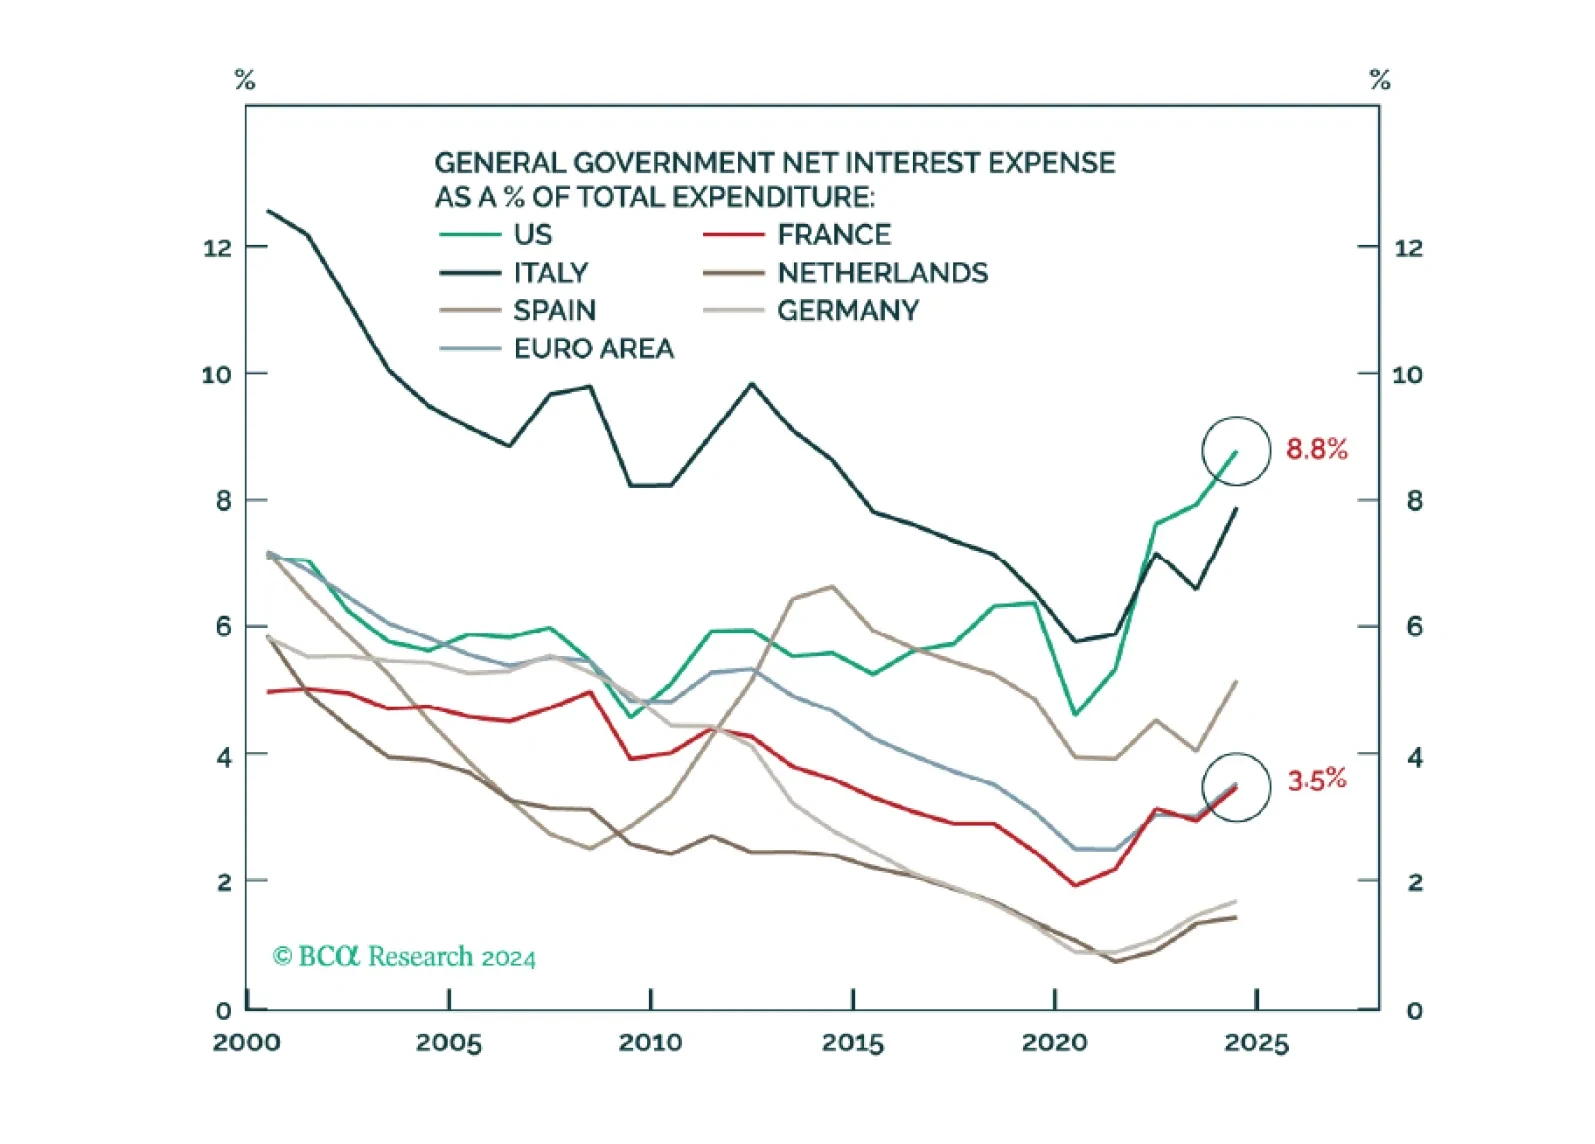
In our Volume I – The Alpha Report – we posit that the French bond market reaction is a mere amuse bouche for what is coming to the US. All year, we have warned investors that US politics could induce a bond market riot. This moment is nigh. Act accordingly!