Latest from BCA Research


The French stock market has never been so cheap versus the US. And its sharp underperformance on its recent political events is irrational given the CAC 40’s limited exposure to French domestic economics and politics. This provides a great buying opportunity both tactically and for the longer term. Plus: stocks versus bonds approaching a potential consolidation phase.

Investors in European sovereign bonds should find solace that continental voters are not turning away from support for EU integration. As such, populist parties are not really that “far” left or right. And as long as they want to maintain popular support, they will have to abide by the fiscal rules imposed by Brussels. No such supranational constraint exists in the U.S., the real risk for global bond operators.

We have turned cautious on equities for the first time since August 2022. Our end-of-the-year target for 2024, 5,500 on the S&P 500, has been reached. From here on out, any upside is gravy. However, we worry about US – not European – politics. In fact, we think investors could profit from the recent selloff in France. The real risks are in the US.
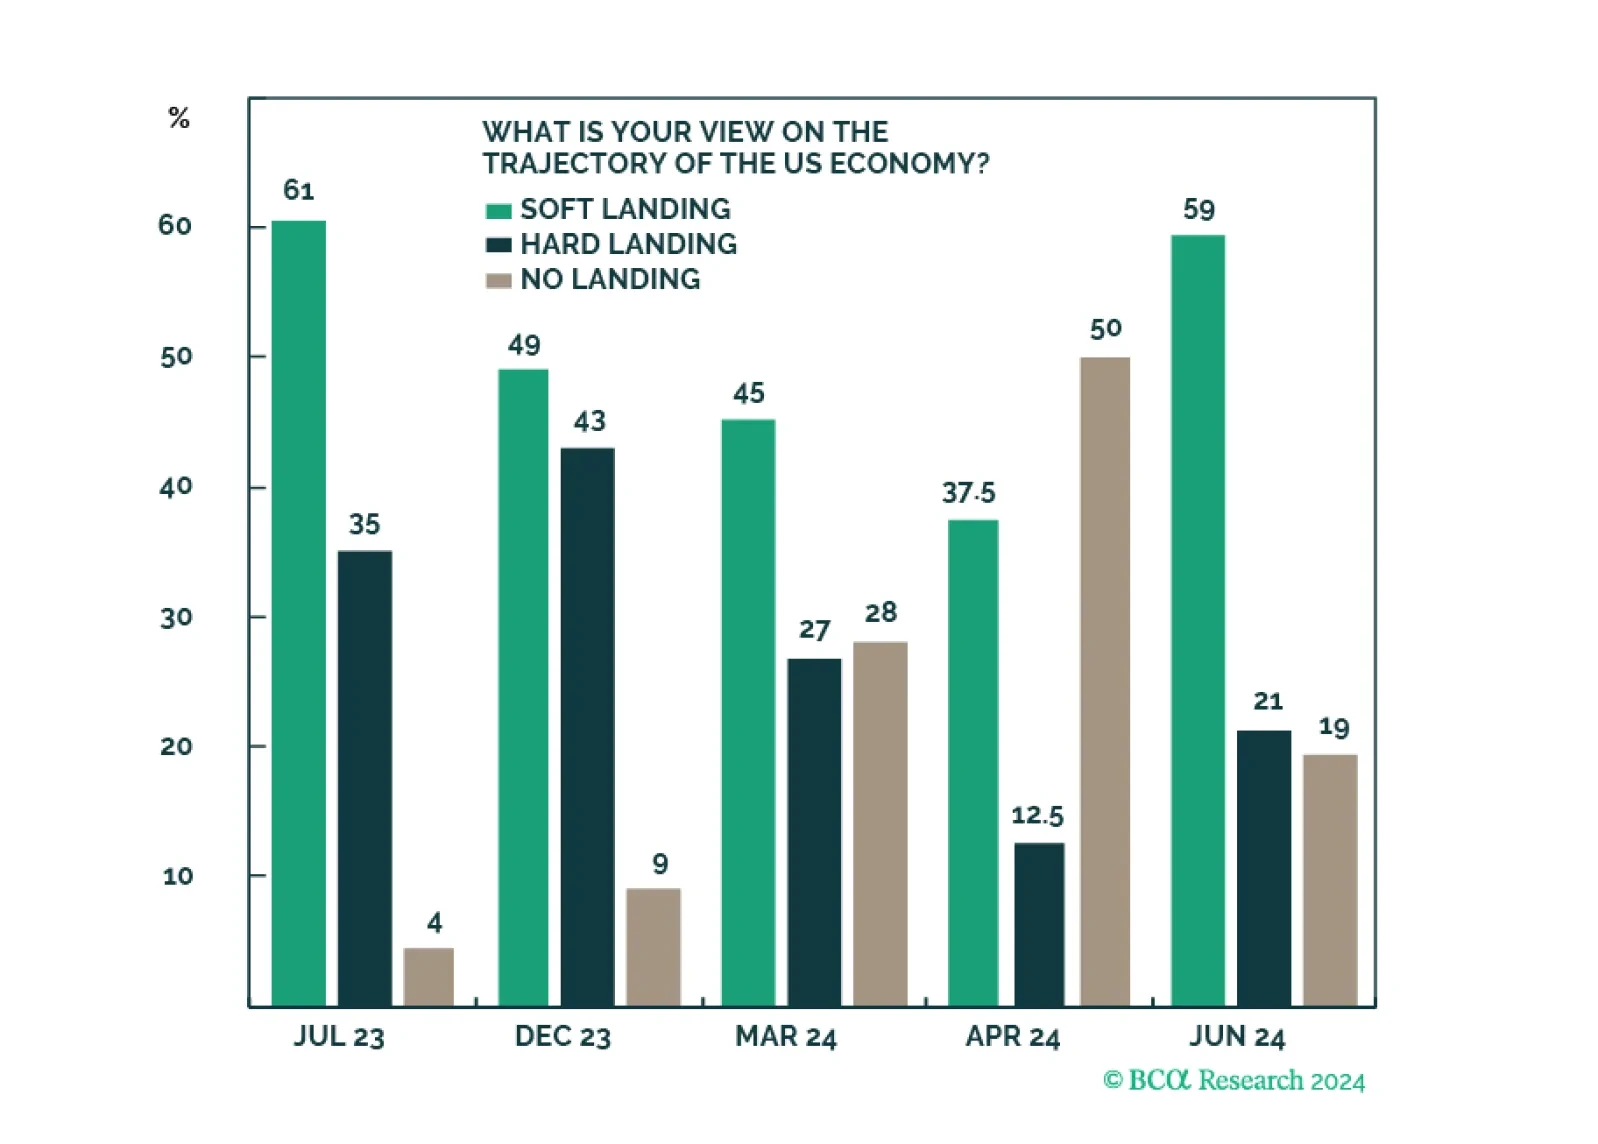
Investors are increasingly more optimistic about the trajectory of the US economy and believe that the “Fed put” is in play limiting the downside. While the majority still have cash to put to work, many are waiting to see if the rally broadens thanks to earnings rebound across non-GenAI sectors. Fairly conservative positioning and expectations of the rangebound markets point to a consensus view that the market may be fully valued, and a soft-landing outcome along with rate cuts, are priced in.
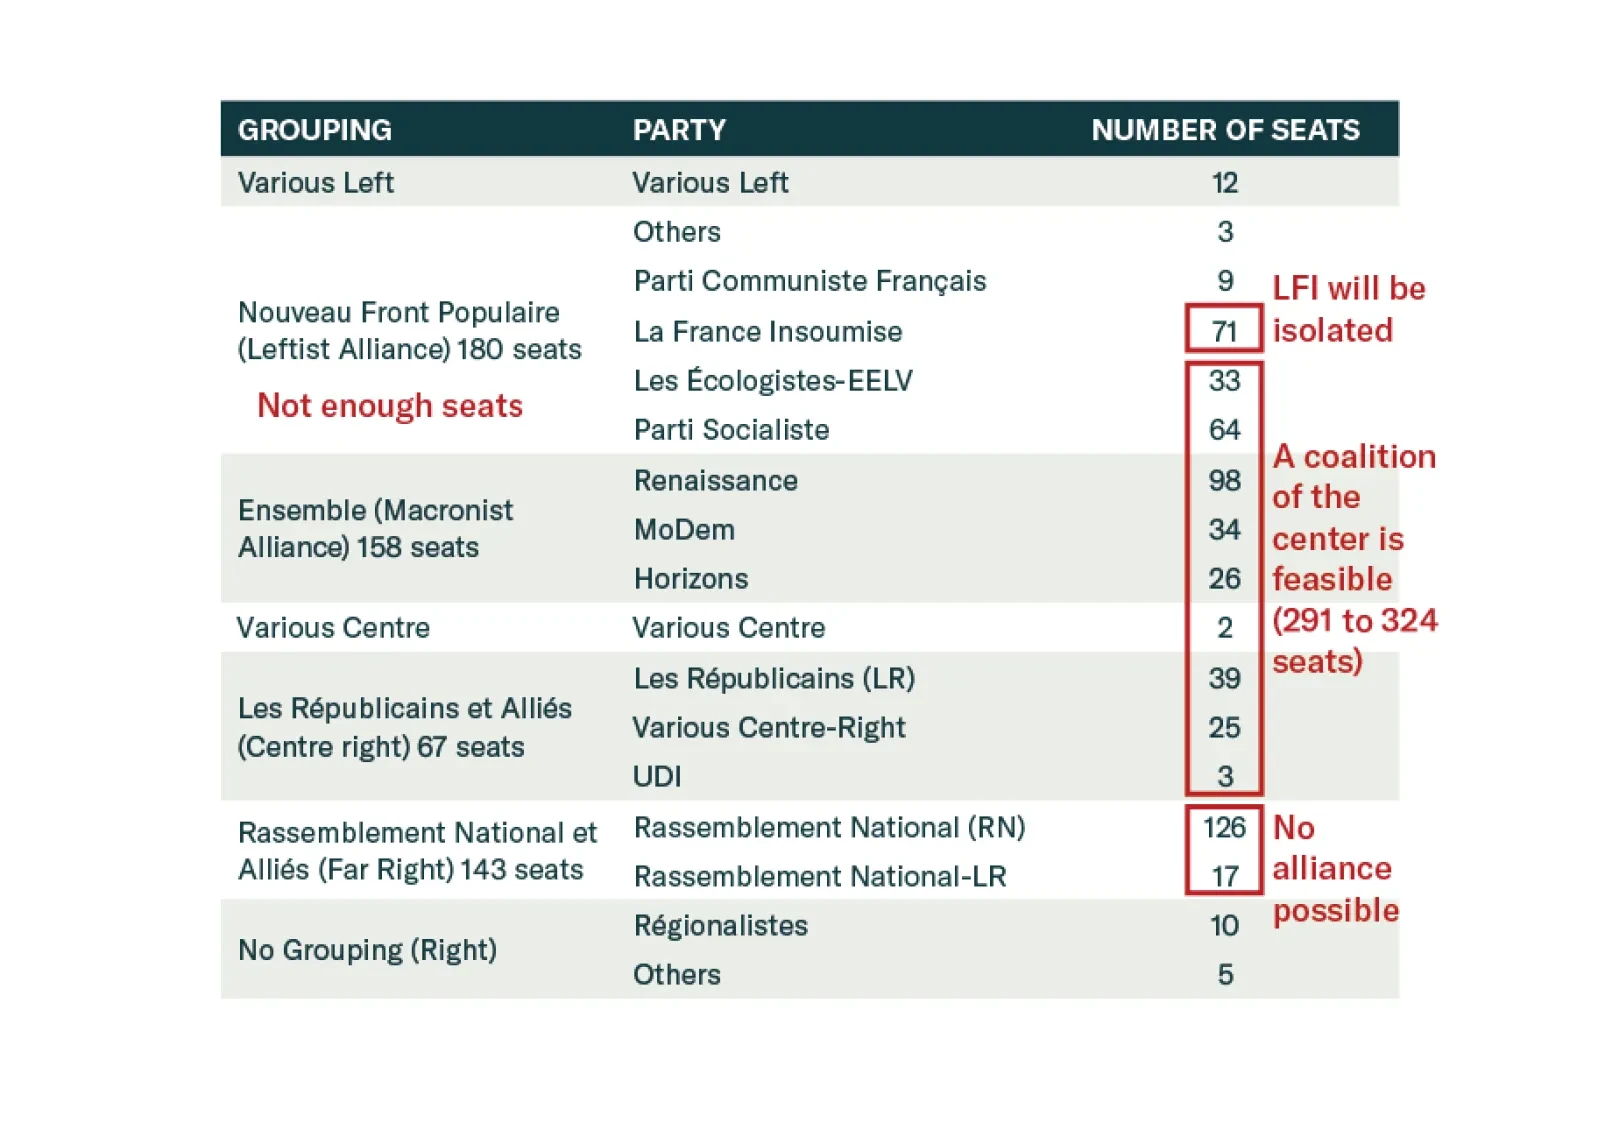
At first glance, France has moved to the far left. However, this coalition is fragile, and Macron’s allies still hold the balance of power. What are the assets that will benefit from this new political setup, and those that will not?
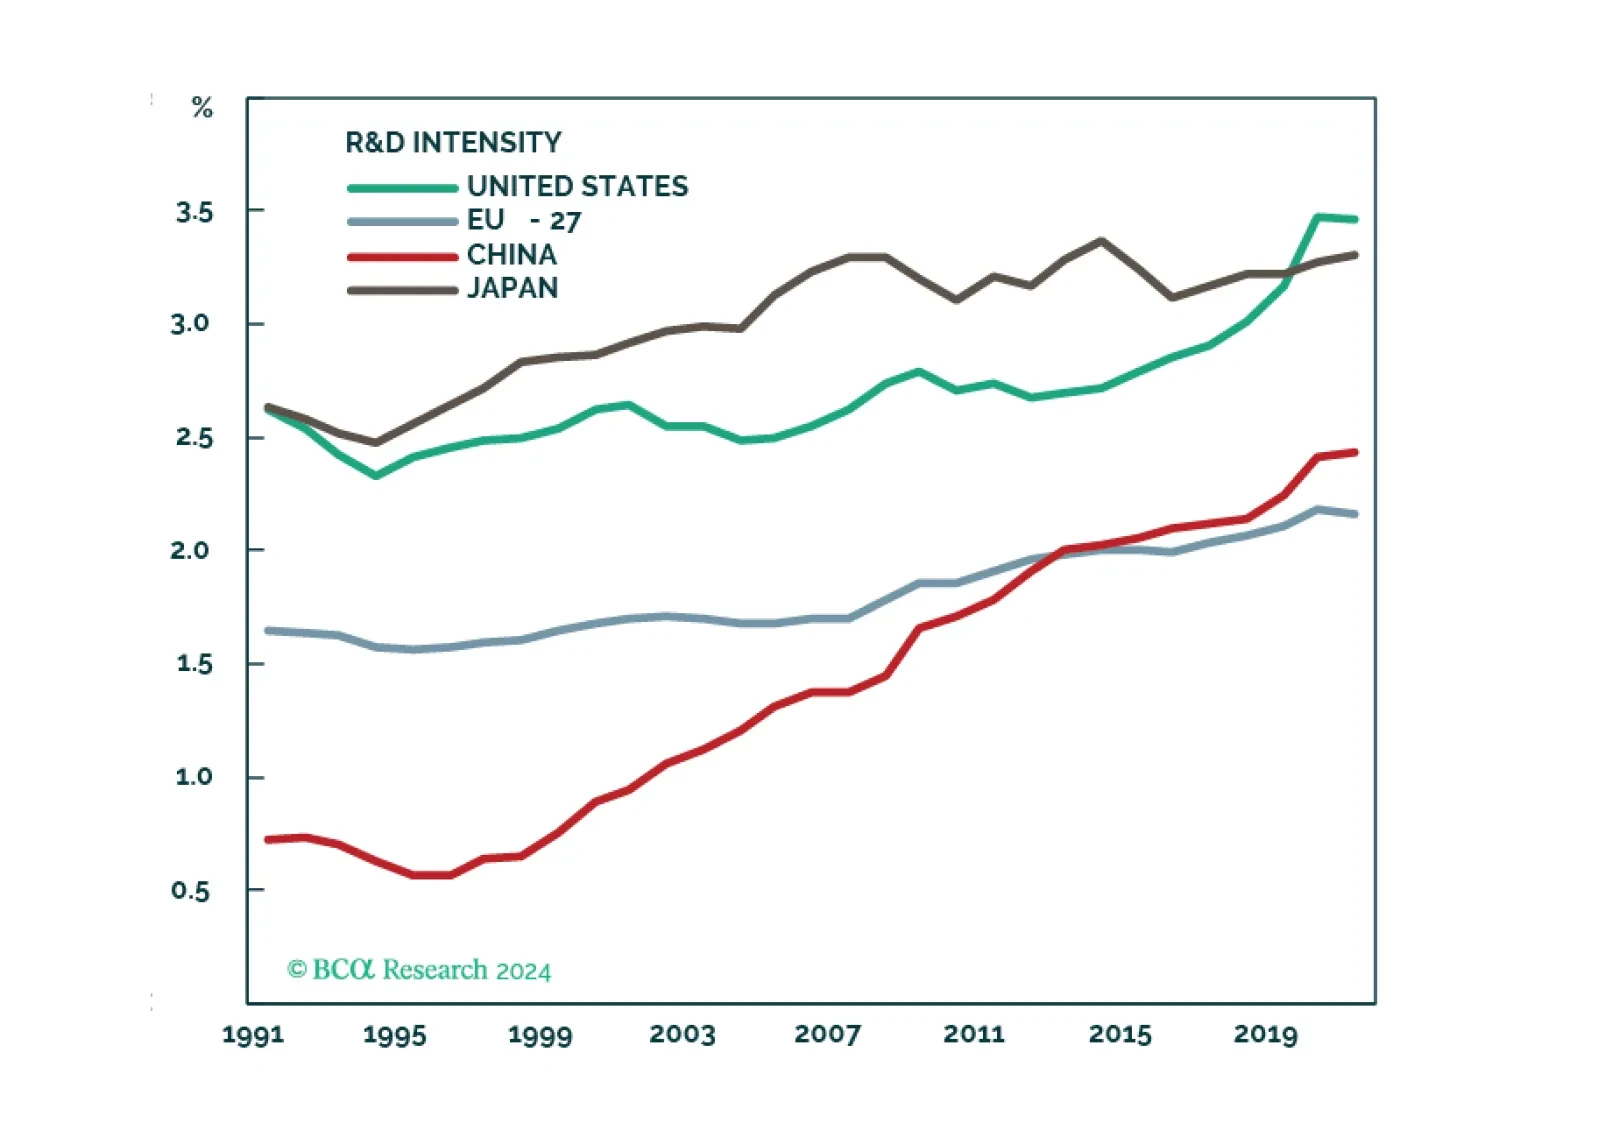
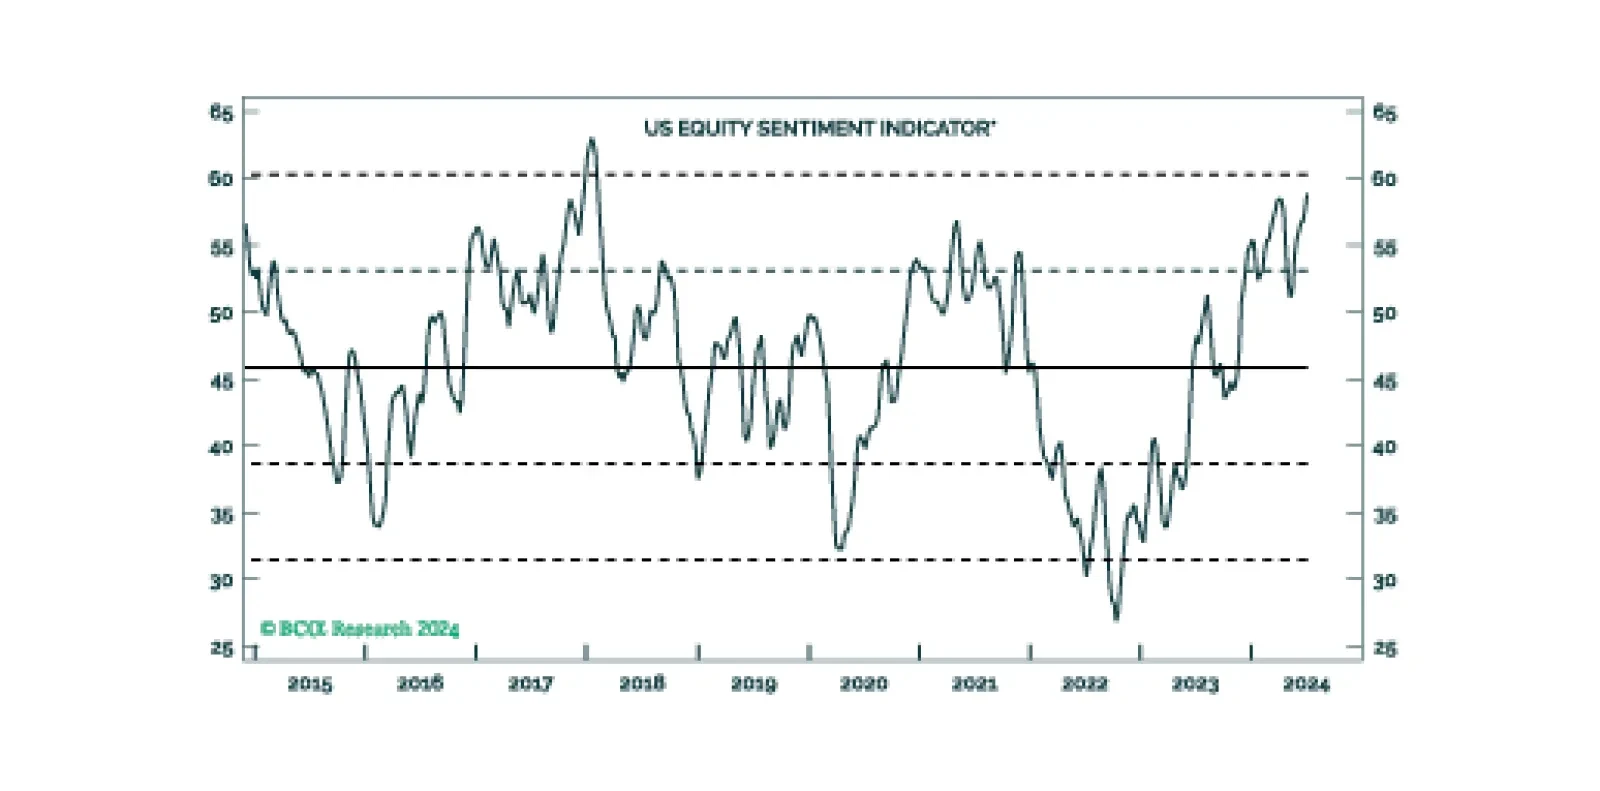
Although we ticked a second box on our checklist, the incoming data still do not indicate that a recession is imminent. We remain tactically equal weight equities with a strong bias to underweight them, but we’re not exiting the party just yet.
In this week's report, we review the impact of political developments, as well as incoming fundamental data, on our positioning.